HOME
49.2.5 A/C Belt Replacement: A Comprehensive Guide

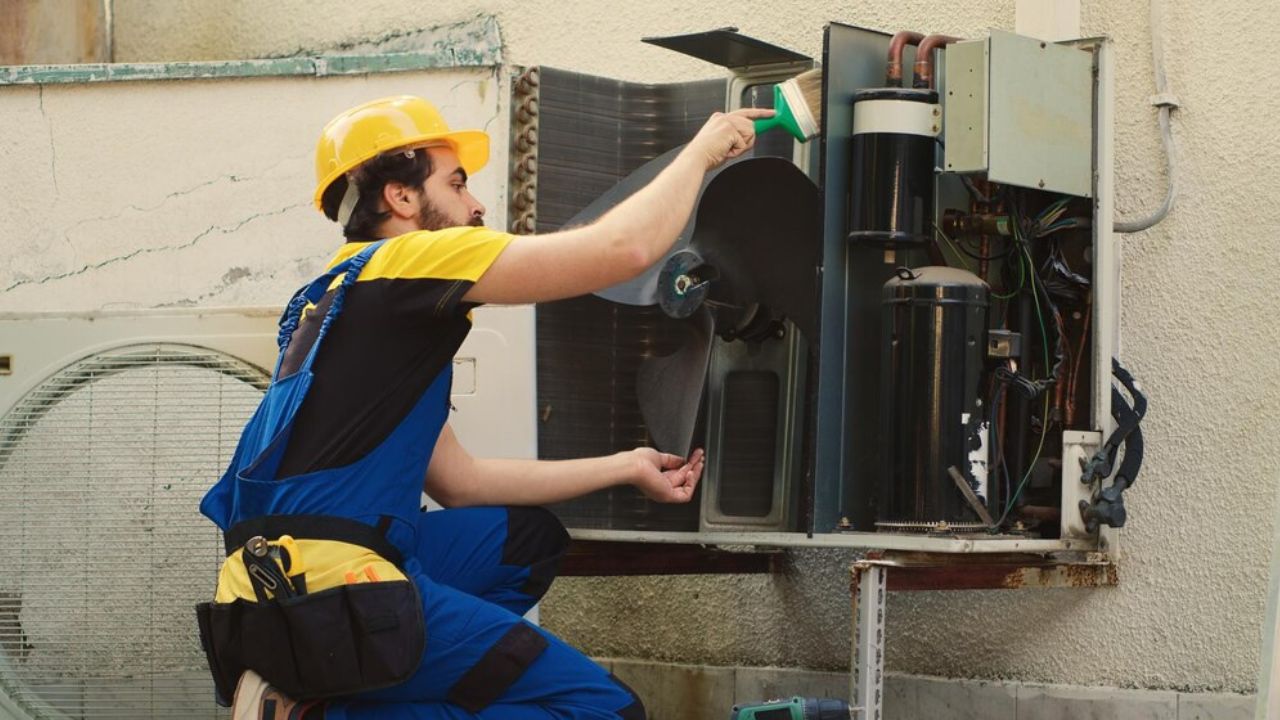
When the temperature rises and the scorching heat becomes unbearable, your car’s air conditioning (A/C) system is your best friend. But what happens when the A/C belt, a crucial component of this system, starts showing signs of wear and tear? If you’re a vehicle enthusiast or a DIYer, understanding how to replace the 49.2.5 A/C belt can save you time and money. This comprehensive guide will walk you through the process, whether you’re a seasoned mechanic or a curious beginner eager to learn.
Understanding the A/C Belt and Its Importance
The 49.2.5 A/C Belt Replacement is a vital part of your vehicle’s air conditioning system, responsible for driving the compressor. This belt ensures that refrigerant circulates properly, maintaining a cool and comfortable environment inside your car. When this belt begins to deteriorate, you might notice reduced cooling efficiency, strange noises, or visible cracks on the belt itself, all of which indicate it’s time for a replacement.
A damaged A/C belt not only affects your comfort but also poses a risk to other engine components. If it snaps, it could damage adjacent parts, leading to costly repairs. Understanding the belt’s function helps underline the importance of timely replacement, ensuring the longevity of your vehicle’s A/C system.
Signs Your A/C Belt Needs Replacement
Recognizing the early signs of a failing A/C belt can prevent further damage and maintain the efficiency of your car’s cooling system. Listen for squealing noises when you start the engine or turn on the A/C. These noises often indicate that the belt is slipping or misaligned. Another sign is if the A/C fails to cool the car adequately, suggesting that the belt isn’t driving the compressor properly.
Visual inspection is an easy way to check the belt’s condition. Look for cracks, fraying, or glazing on the belt’s surface. If you notice any of these signs, it’s time to consider a replacement. Addressing the issue promptly can prevent a complete breakdown of your A/C system and avoid unexpected repair costs.
Tools You Need for A/C Belt Replacement
Before you start the replacement process, gather the necessary tools to ensure a smooth and efficient experience. A basic toolkit is essential, including a socket set, wrenches, and screwdrivers. Having a serpentine belt tool can make the job easier, allowing you to loosen the tensioner with minimal effort.
Safety gear is just as important. Equip yourself with safety glasses and gloves to protect against any accidents during the replacement process. A flashlight can be invaluable for illuminating the engine bay, ensuring you can see the belt and surrounding components clearly.
Preparing Your Vehicle for A/C Belt Replacement
Start by parking your vehicle on a level surface and engaging the parking brake. Ensure the engine is off and cool to prevent accidents or injuries. Open the hood and disconnect the battery to eliminate the risk of electrical shock while working on the vehicle.
Gather all your tools and lay them out within reach. Having everything you need at hand will streamline the process, allowing you to focus on replacing the belt without unnecessary interruptions. This preparation sets the stage for a successful replacement, minimizing hassle and maximizing safety.
Removing the Old A/C Belt
Begin by locating the serpentine belt tensioner. This component maintains the tension on the belt and will need to be loosened to remove the old belt. Use your serpentine belt tool or a suitable wrench to rotate the tensioner counterclockwise, releasing the tension on the belt.
With the tension relieved, carefully slide the old belt off the pulleys. Take note of the belt’s routing across various pulleys, as you’ll need to replicate this pattern when installing the new belt. Removing the old belt is a straightforward process, laying the groundwork for the next steps in this replacement guide.
Choosing the Right Replacement Belt
Selecting the correct replacement belt is crucial for optimal performance. Refer to your vehicle’s manual or check the existing belt for size specifications. Ensure you purchase a quality belt from a reputable manufacturer to avoid premature wear and potential failures.
When buying a new belt, consider the material and construction. High-quality belts are often made from durable materials like EPDM rubber, designed to withstand heat and stress. Investing in a reliable belt ensures the longevity of your A/C system and contributes to a smoother driving experience.
Installing the New A/C Belt
With the old belt removed and the correct replacement in hand, it’s time to install the new A/C belt. Begin by routing the belt around the pulleys, following the pattern you noted earlier. Double-check the alignment to prevent misplacement, which can lead to uneven wear or slippage.
Once the belt is in position, use the serpentine belt tool to apply tension by rotating the tensioner clockwise. Ensure the belt is snug but not overly tight, as excessive tension can damage both the belt and the pulleys. Proper installation is key to maintaining the efficiency and reliability of your A/C system.
Testing the A/C System
After installing the new belt, it’s crucial to test the A/C system to ensure everything is functioning as expected. Reconnect the battery and start the engine, listening for any unusual noises that might indicate a problem. Turn on the A/C and check for proper cooling.
Inspect the belt visually while the engine is running, verifying that it’s running smoothly across the pulleys. If any issues arise, revisit the installation process to correct any errors. A thorough test confirms the success of your replacement, ensuring your A/C system is ready to tackle the heat.
Tips for Maintaining Your New A/C Belt
Regular maintenance can extend the life of your new A/C belt, ensuring consistent performance from your vehicle’s cooling system. Periodically inspect the belt for signs of wear or damage, addressing issues promptly to prevent breakdowns.
Keep your engine bay clean to reduce the accumulation of dirt and debris, which can accelerate wear. Additionally, consider consulting your vehicle’s maintenance schedule for specific recommendations on belt inspections and replacements, aligning with manufacturer guidelines for optimal care.
Common Mistakes to Avoid During Replacement
Even seasoned DIYers can make mistakes during A/C belt replacement. Avoid over-tightening the belt, as excessive tension can lead to premature wear or damage to the pulleys. Ensure the belt is routed correctly to prevent slippage or misalignment.
Neglecting to inspect other components like the tensioner or pulleys can lead to future problems. Take the opportunity to check these parts for wear or damage, replacing them if necessary. By avoiding these common pitfalls, you can ensure a successful replacement and prolong the life of your A/C system.
When to Seek Professional Help
While replacing an A/C belt can be a straightforward task, some situations warrant professional assistance. If you encounter complex issues like seized pulleys or stripped bolts, consulting a professional mechanic can prevent further damage.
Additionally, if you’re unsure about any step in the process, seeking expert help can provide peace of mind and ensure the job is done correctly. Remember, there’s no shame in reaching out for assistance, especially when it comes to maintaining your vehicle’s performance and safety.
The Benefits of Regular A/C Maintenance
Regular maintenance of your vehicle’s A/C system offers numerous benefits beyond just comfort. It can improve fuel efficiency, as a well-functioning A/C system doesn’t overtax the engine. Additionally, routine checks can prevent costly repairs by identifying and addressing minor issues before they escalate.
Maintaining your A/C system also enhances your driving experience, ensuring a comfortable environment regardless of external temperatures. By committing to regular inspections and timely replacements, you can enjoy a reliable and efficient air conditioning system year-round.
Conclusion
Replacing the A/C belt may seem daunting, but with the right knowledge and tools, it’s a task well within the reach of most car enthusiasts. Understanding the importance of this component and following a systematic approach ensures a successful replacement, preserving the performance of your vehicle’s A/C system.
Don’t wait for discomfort or damage to dictate your actions—take proactive steps to maintain your car’s cooling capabilities. Whether you tackle the replacement yourself or consult a professional, prioritizing this task guarantees a cooler, more comfortable driving experience, no matter how high the temperature climbs.
Buying a home can feel out of reach when your financial life does not fit the standard pattern of one employer, regular pay stubs, and a long credit history. Families with contract income, multiple jobs, recent moves, or limited U.S. credit can still take meaningful steps toward becoming stronger applicants. Some borrowers may also explore ITIN mortgage loans when traditional documentation or identification requirements do not reflect their circumstances.
The goal is not to make your finances look different from what they are. It is to organize an accurate, consistent picture of how you earn, spend, save, and pay your obligations. Early preparation can help you identify gaps, answer lenders’ questions more quickly, and make a more confident decision about the price range that fits your household.
Why Financial Records Matter
Mortgage lenders generally assess an applicant’s ability to repay a loan by reviewing income, debts, available funds, credit information, and other application details. A credit score is important, but it does not always tell the full story. For example, a renter may have a reliable history of paying rent on time while having few accounts reported to the major credit bureaus.
Organized records help show the pattern behind the numbers. The Consumer Financial Protection Bureau recommends that buyers prepare by reviewing their credit, assessing their finances, setting a home-price budget, and gathering application materials before shopping for a mortgage. This can make it easier to spot issues before they become a time-sensitive problem.
What Nontraditional Financial History Means
Nontraditional financial history is a practical description of circumstances that may not appear neatly in a conventional mortgage file. It can include a thin credit profile, self-employment, contract work, income from several jobs, a short U.S. credit history, or recurring payments that are not consistently reported on a credit report.
- Self-employment, freelance work, tips, commissions, or seasonal earnings
- Income received through more than one employer or client
- Verified rent, utility, insurance, or phone payments
- Recent relocation or newly established credit accounts
- Documented savings built gradually over time
Documents to Gather Before Applying
Create one secure digital folder and keep paper copies when useful. A lender may request different items depending on the loan and borrower, but a well-organized file can reduce back-and-forth questions.
- Recent bank statements and earnings statements
- Pay stubs, tax returns, tax transcripts, 1099 forms, or business records when applicable
- Invoices, contracts, and payment records for contract or self-employed income
- Rental receipts or a landlord-provided payment history
- Utility, insurance, and other recurring payment records
- Statements for current debts and monthly obligations
- Identification documents and proof of the source of down payment funds
How Alternative Credit May Help
Some lending programs and lenders may review verified payment records beyond standard credit accounts. These records can help demonstrate a pattern of meeting recurring obligations, especially when a borrower has limited traditional credit. They are not a substitute for the full application review, and acceptance varies by lender and loan program.
Records That May Be Useful
- Rent payments made through a traceable method
- Electric, gas, water, internet, or phone bills
- Auto, renters, health, or other insurance payments
- Child care, tuition, or similar recurring obligations
Keep records that clearly identify the account holder, the payment amount, the due date, and the payment date. Cash payments can be difficult to verify without receipts, bank withdrawals, or a written payment history from the recipient.
How to Organize Different Income Sources
Families with multiple income sources should make the connection between the work performed and the money received easy to follow. A contractor, for example, can keep invoices, signed agreements, deposit records, and tax documents together to show how business income is deposited into a personal account.
- List every household income source and how often it is paid.
- Separate business and personal transactions when possible.
- Keep invoices, contracts, and deposit records in date order.
- Be ready to explain large or unusual deposits.
- Avoid moving money between accounts without retaining a clear paper trail.
How to Build a Realistic Homebuying Budget
The amount a lender may approve is not always the amount that feels comfortable for your family. Build your budget around the full monthly housing cost, including principal and interest, property taxes, homeowners’ insurance, mortgage insurance if required, homeowners’ association dues if applicable, utilities, and expected maintenance.
Also plan for upfront costs such as the down payment, closing costs, moving expenses, and immediate repairs or purchases. Review several months of actual spending before setting a target payment. The CFPB advises buyers to compare mortgage offers from multiple lenders, which can help households evaluate loan terms and costs rather than focusing on one advertised rate. This gives buyers a practical framework for that process.
Questions to Ask a Mortgage Professional
- Which documents can be used to verify my income?
- Can verified rent or utility payments be considered in this program?
- How much payment history is needed?
- How are self-employed, contract, commission, or seasonal earnings reviewed?
- Which funds may be used for the down payment and closing costs?
- What fees are due before closing, and what costs are included in the estimate?
- Would a co-borrower change the available options?
Mistakes That Can Slow Down an Application
- Applying before checking credit reports for errors or missing information
- Leaving large deposits unexplained
- Taking on new debt or opening unnecessary credit accounts before closing
- Changing jobs or income structure without discussing it with the lender
- Using cash without maintaining receipts or other documentation
- Underestimating taxes, insurance, repairs, and moving costs
A Step-by-Step Preparation Plan
- Set a price range. Base it on the full monthly cost and your household budget.
- Review credit and debts. Correct errors and understand existing monthly obligations.
- Build a document folder. Save bank, income, tax, rent, and payment records in one place.
- Track savings. Keep a clear record of where the down payment and closing funds come from.
- Speak with qualified lenders. Ask how each one reviews your specific financial records.
- Keep records current. Continue documenting income, payments, and account activity through closing.
Final Thoughts
Homeownership preparation is not limited to households with a long, conventional credit history. Clear records, steady financial habits, realistic budgeting, and early conversations with mortgage professionals can help families present a more complete application. Start by organizing the facts, protecting your savings, and choosing a home payment that supports your life after closing.
HOME
How to Plan Laser Hair Removal Around Skin Tone, Hair Growth, and Seasonal Sun Exposure in Centennial, Colorado

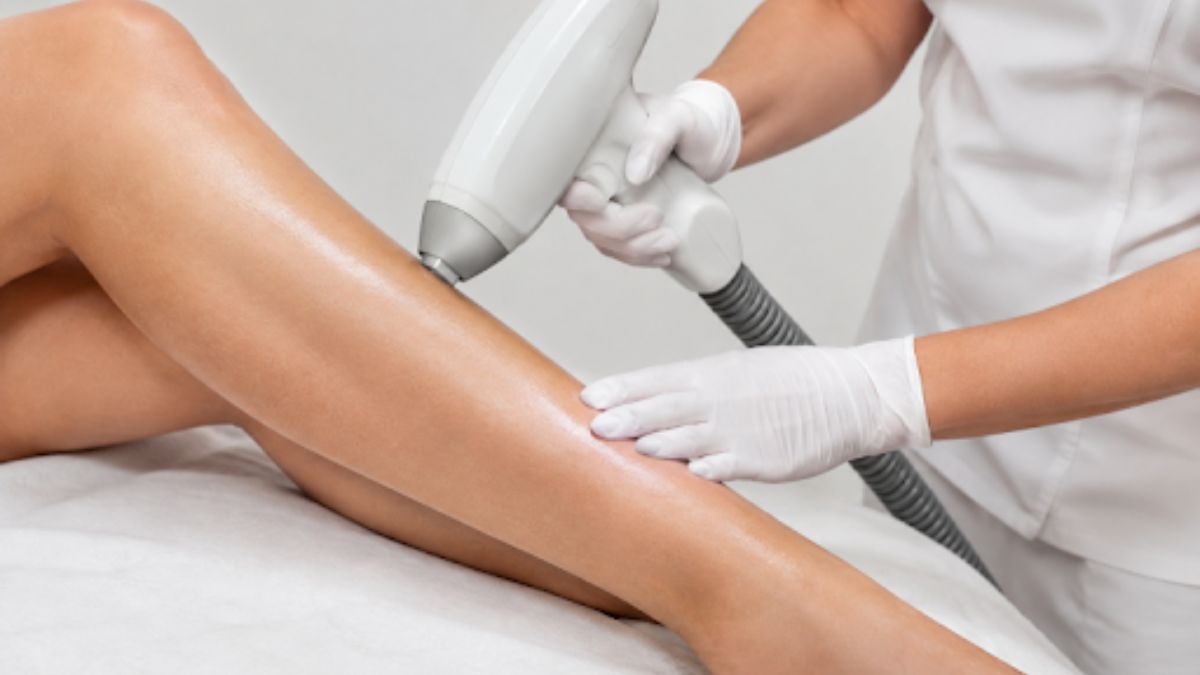
Planning laser hair removal in Centennial, Colorado, involves more than choosing a convenient appointment date. The timing should account for your hair growth pattern, your skin’s current condition, and how much sun exposure is likely during work, recreation, travel, and daily life along the Front Range.
For local clients comparing options, Hair To Bare South offers laser hair removal services Centennial, CO with treatment options organized by small, medium, large, and extra-large areas. Its service information helps Centennial-area clients understand the range of areas that may be treated and why a consistent, safety-focused plan matters when working toward long-term hair reduction.
Why Treatment Timing Matters
Laser hair removal is not typically a one-visit solution. The laser is designed to target pigment associated with the hair and follicle, but only some follicles are in the most responsive stage at a given time. That is why appointments are commonly spread across a series rather than scheduled back-to-back.
According to the American Academy of Dermatology’s laser hair removal guidance, many patients can be treated about every four to six weeks, although the appropriate interval depends on the person and area treated. A provider should set the schedule based on visible regrowth, skin response, and treatment goals.
How the Hair Growth Cycle Affects Results
Hair moves through several broad growth phases. Understanding them can make the treatment process feel less mysterious.
Active growth
During the active growth stage, often called anagen, the follicle has a stronger connection to the hair being treated. This is generally the stage in which laser treatment is most useful.
Transition and resting
In the transition stage, growth slows. In the resting stage, the follicle does not produce a new visible hair in the same way. Since neighboring follicles can be in different phases, one session cannot address every hair at once.
Consistency is more valuable than rushing. Scheduling too frequently does not necessarily create faster results, while long, irregular gaps can make it harder to follow a clear plan for recurring growth.
Skin Tone, Hair Color, and Hair Texture
Darker, coarser hair often provides a clearer target because it contains more pigment. Fine blonde, gray, white, and some red hair can be more difficult for laser-based treatment to detect and reduce. That does not mean a consultation is pointless, but it does mean expectations should be discussed honestly before treatment begins.
People with darker skin tones may be candidates for laser hair removal, but device selection, settings, and provider experience become especially important. Ask how the provider evaluates skin coloring and how they reduce the risk of burns, irritation, or unwanted pigment changes. A careful consultation should never treat skin tone or hair type as an afterthought.
Seasonal Planning for Centennial Sun Exposure
There is no single best season for every person, but Centennial’s bright weather and outdoor lifestyle can affect the practical side of planning. Ski days, patio time, hikes, golf, and warm-weather trips can all increase sun exposure, including when temperatures feel cool.
- Winter: Less exposed skin and fewer tanning opportunities may make aftercare easier for some people.
- Spring: Starting early can provide time for a series of sessions before summer activities become frequent.
- Summer: Treatment may still be possible, but it requires careful communication about recent sun, tanning, and travel plans.
- Fall: This can be a practical point to begin or resume a treatment series after a more sun-intensive season.
The importance of planning ahead for warmer weather is especially relevant when you expect pool days, vacations, or prolonged outdoor events. Recent tanning, including indoor tanning and self-tanning products, should be disclosed so the provider can determine whether treatment should proceed or be postponed.
Why Treatment Area Changes the Timeline
Small areas such as the upper lip, chin, or underarms can take less appointment time than the legs, back, or chest. However, a shorter appointment does not always mean a shorter overall course of treatment. Hair density, thickness, and hormonal influence can vary substantially from one body area to another.
For example, someone may notice meaningful changes in underarm hair before seeing the same degree of reduction on the legs. Facial hair can require added patience because it may be finer or influenced by hormonal changes. Maintenance visits may be useful for some people after the initial series, particularly when new growth develops over time.
Simple Steps to Prepare
- Avoid tanning and follow the provider’s instructions about sun exposure.
- Share medications, skin conditions, recent cosmetic procedures, and any history of unusual scarring.
- Ask whether shaving is recommended before your appointment.
- Avoid waxing, plucking, or epilating when the provider advises leaving the follicle intact.
- Arrive with clean skin and avoid products that may irritate the treatment area.
- Wear soft, comfortable clothing that will not rub against freshly treated skin.
Questions to Ask Before Booking
- What experience do you have with my skin tone and hair type?
- Which laser or light-based device will you use?
- How many appointments may be appropriate for this area?
- How far apart should my sessions be scheduled?
- What should I avoid before and after each appointment?
- Which side effects are expected, and which require follow-up?
- Would a consultation or test spot be appropriate?
Realistic Results and Long-Term Planning
It is more accurate to think in terms of permanent hair reduction than guaranteed removal of every hair forever. Results differ by skin tone, hair characteristics, hormonal changes, area treated, device, and appointment consistency. A trustworthy provider explains those variables clearly instead of promising identical results for everyone.
A strong consultation includes a review of recent sun exposure, a plain-language timeline, discussion of possible side effects, and a plan tailored to the individual. In Centennial, the best laser hair removal schedule is usually the one that protects your skin, fits your calendar, and gives each treatment enough time to work.
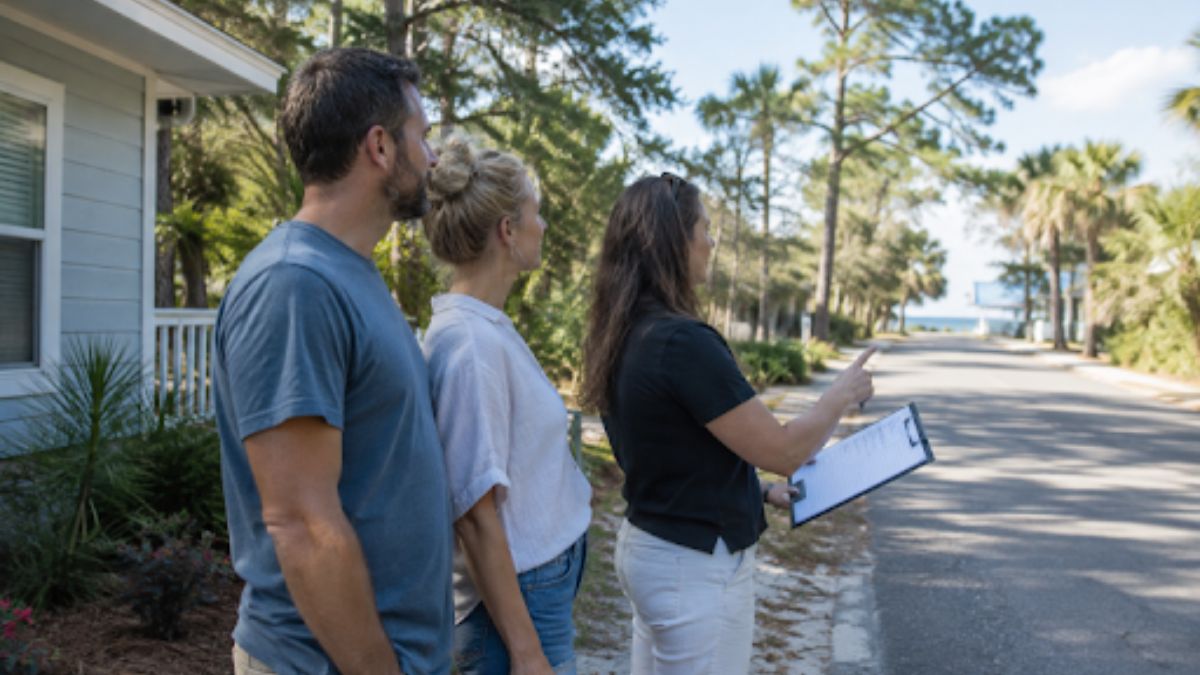
Buying near the water in Pensacola, Florida, can mean very different things depending on whether you picture a downtown-adjacent neighborhood, a Gulf Breeze home near the bay, a quieter Navarre address, or a beach property with sand and water views close by. The best choice is usually not the community with the lowest list price or the shortest walk to the shore. It is the one that fits your budget, routines, risk tolerance, and long-term plans.
For help sorting through those differences, Pensacola real estate agents Coastal Collective Group offers buyer, relocation, waterfront, luxury, and investment-property guidance across Greater Pensacola. Coastal Collective Group is a local real estate team serving Pensacola, Gulf Breeze, Navarre, Pensacola Beach, and Navarre Beach, making it a useful starting point for buyers who need neighborhood-level insight rather than a one-size-fits-all coastal search.
Why the Community Matters as Much as the Home
Two homes with similar prices can create very different ownership experiences. A larger inland home may provide more storage, yard space, and easier access to everyday errands. A smaller beach-area condo may offer views and recreation, but also add association obligations, seasonal activity, and building-level maintenance considerations. The goal is to compare ordinary weekdays, storm preparation, and long-term upkeep, not just a sunny weekend showing.
Start With the Property’s Main Job
- Primary residence: Prioritize work routes, healthcare, schools, groceries, and year-round services.
- Second home: Look for practical lock-and-leave features, manageable maintenance, and convenient arrival routes.
- Vacation rental: Review local requirements, association rules, rental limits, and realistic operating expenses before relying on projected income.
- Investment property: Consider demand, vacancies, repairs, taxes, financing, and the resale market for comparable homes.
- Retirement home: Evaluate access to medical care, home layout, walkability, storm readiness, and ongoing upkeep.
Compare Pensacola-Area Communities by Lifestyle
Pensacola
Pensacola can suit buyers who want a wider range of housing styles and access to downtown, employment centers, restaurants, healthcare, shopping, and airport travel. The city includes established neighborhoods, historic areas, newer developments, and waterfront-adjacent options, so buyers should compare individual neighborhoods rather than treating Pensacola as a single, uniform market.
Gulf Breeze
Gulf Breeze appeals to buyers seeking a primarily residential setting with access to Pensacola and nearby beach areas. Test important routes at the times you would actually use them, especially when bridge access affects the trip. For each property, examine lot drainage, flood information, insurance estimates, nearby services, and the practical distance to work or school.
Navarre
Navarre offers a different pace, with mainland neighborhoods, newer homes, and beach access. Carefully compare mainland Navarre with Navarre Beach. A home may be close to the water yet have a very different commute, lot size, insurance profile, rental environment, and availability of everyday services than another property only a few miles away.
Pensacola Beach and Navarre Beach
These beach communities offer direct coastal recreation, water views, and a distinct vacation-oriented atmosphere. They also require close attention to storm exposure, wind and flood insurance, seasonal traffic, shared-building responsibilities, and ownership structure. With a condo or townhome, request the association budget, reserve information, rules, insurance details, meeting minutes, and any information about pending assessments.
Build a Realistic Total-Cost Estimate
Your purchase price is only one part of the decision. Create monthly and annual estimates that include the mortgage, property taxes, homeowners’ insurance, flood coverage when applicable, HOA or condo fees, utilities, maintenance, and travel costs. For waterfront homes, also consider exterior materials, roofs, docks, seawalls, pools, landscaping, and marine-related maintenance. Request insurance quotes for the exact address, because roof age, construction, elevation, and prior claims can affect cost.
Check Flood Exposure and Coastal Risk
Flood risk should be reviewed at the address level, rather than assumed based on a neighborhood name or a nearby property. Use the FEMA Flood Map Service Center to review the property’s mapped flood information, then ask for available elevation documentation and seller disclosures. During inspections, look closely at drainage, roof condition, windows, doors, foundation type, and storm-protection features. A lower-risk map designation does not mean flooding is impossible, so buyers should still consider drainage patterns, coverage options, and their own financial comfort level.
Review Commutes and Everyday Access
Drive key routes during morning and afternoon work periods, weekends, and a busy beach-season day when possible. Check the trip to work, schools, hospitals, pharmacies, grocery stores, military facilities, and the airport. Online map estimates are useful, but they cannot fully show how a route feels during a real errand run or after an event. Confirm school assignments directly with the appropriate district because boundaries and enrollment policies can change.
Match the Property Type to Your Lifestyle
- Single-family homes: Often provide privacy, storage, parking, and yard space. Review drainage, trees, fencing, exterior materials, roof age, and storm preparedness.
- Condos and townhomes: Can reduce personal exterior maintenance, but buyers should understand fees, rules, insurance responsibilities, parking, pets, rentals, reserves, and assessments.
- Waterfront homes: Require careful review of docks, lifts, seawalls, erosion, water depth, access, permits, and maintenance responsibilities. Waterfront does not automatically mean the same boating access or insurance profile.
Use Local Data, Not Broad Headlines
National real estate headlines rarely accurately describe every segment of the Pensacola area. Compare recent closed sales, active listings, pending properties, and days on market for homes that closely match the property type, location, condition, and amenities you are considering. Beach condos, inland family homes, luxury residences, and rental-oriented properties can behave differently, even within the same broader area.
Questions to Ask Before Making an Offer
- What will the total monthly ownership cost be after insurance, fees, taxes, and maintenance?
- Is flood insurance required, available, recommended, or excluded from the current quote?
- What repairs or replacements may be needed within the next five years?
- Do HOA rules affect rentals, renovations, pets, boats, parking, or exterior changes?
- Are there any planned changes to roads, drainage, construction, or development nearby?
- Which recent sales are the most relevant comparisons for this specific home?
A Simple Community Comparison Worksheet
Score each community from one to five, then write a few notes beside every category:
- Purchase price: Compare similar homes, not broad averages.
- Insurance and flood exposure: Use quotes and documents tied to the specific address.
- Commute and access: Test important routes during busy periods.
- Daily lifestyle: Consider quiet time, recreation, restaurants, parks, and errands.
- Maintenance needs: Include roofs, pools, yards, docks, seawalls, and shared amenities.
- Long-term fit: Consider future household needs, resale potential, and changing priorities.
Common Buyer Questions
Is it better to live near the beach or inland?
Neither option is automatically better. Inland homes may offer more space and fewer coastal maintenance concerns, while beach-area homes can provide closer access to water and recreation. The right answer depends on budget, insurance tolerance, maintenance preferences, and how often you expect to use the beach lifestyle.
Should buyers visit in more than one season?
Yes. A second visit during a different time of year can reveal changes in traffic, parking, noise, rental activity, weather, and the pace of daily life.
Choose the Community That Fits Real Life
The strongest Pensacola-area purchase balances lifestyle with practical ownership. By comparing community character, total cost, commute patterns, coastal exposure, property condition, and future plans, buyers can choose a home that works just as well on a normal Tuesday as it does on a bright Gulf Coast weekend.
-
 HEALTH2 years ago
Integrating Semaglutide into Your Weight Loss Plan: A Practical Guide
-
 HOME IMPROVEMENT2 years ago
How to Choose the Perfect Neutral Area Rug for Every Room
-
 FASHION2 years ago
7 Celebrity-Inspired Elegant Summer Dresses For 2024
-
 HOME2 years ago
Sandra Orlow: The Teen Model Who Captivated the Internet
-
 LAW2 years ago
Teenage Drivers and Car Accidents in California: Risks and Parental Liability
-
 CONSTRUCTION2 years ago
Construction Site Safety Regulations in New York and Your Rights as a Worker
-
 LAW2 years ago
Post-Divorce Considerations in California: Modifications and Long-Term Planning
-
 FINANCE2 years ago
Digital Asset Management in Florida Estate Planning