HOME
The Importance of Understanding Why You Spend

When it comes to managing your finances, one of the most powerful things you can do is understand why you spend money. It’s easy to focus only on how much you’re spending, but understanding the reasons behind your spending decisions is crucial for taking control of your financial future. By doing so, you can uncover potential areas of overspending, recognize emotional triggers that lead to unnecessary purchases, and make better, more informed choices about your money.
For those struggling with credit card debt consolidation, understanding your spending habits is even more important. Once you’ve taken steps to consolidate debt, the next challenge is ensuring you don’t fall back into old spending patterns. By examining the “why” behind your purchases, you can avoid repeating the cycle of debt and start building healthier financial habits. So let’s dive into why understanding your spending is such a critical piece of the puzzle when it comes to achieving your financial goals.
- The Psychology of Spending
People often think of spending as a simple exchange of money for goods or services. However, the psychology behind our spending decisions is much more complex. Your spending habits are often influenced by emotions, stress, social pressures, or even subconscious beliefs. Understanding the emotional triggers behind your purchases can give you the power to take back control.
For example, some people spend when they’re feeling stressed, anxious, or down. They might find comfort in buying something new, even if they don’t need it. This is sometimes called “retail therapy.” Others may spend in response to social pressures—buying the latest gadgets or clothes to keep up with friends or social media influencers. Whatever the trigger, recognizing that these emotional drivers exist can help you take a step back and think critically before making a purchase.
Understanding why you spend is about acknowledging these influences and gaining awareness of how they shape your financial behavior. This awareness can help you break free from unhealthy spending patterns and make more thoughtful, intentional decisions with your money.
- Identifying Areas of Overspending
Once you understand the psychological factors that influence your spending, you can begin to identify areas where you might be overspending. Many of us have certain “problem areas” where we tend to spend more than we realize. For some, it could be eating out too often, while for others, it might be impulse shopping or regularly splurging on non-essential items.
Tracking your spending is an excellent way to identify these patterns. By reviewing your bank and credit card statements, you can see exactly where your money is going. This gives you the opportunity to pinpoint areas where you might be overindulging. Once you’ve identified these areas, you can start making adjustments.
If you’re dealing with credit card debt, cutting back on these overspending habits can help you pay off your debt faster. With a clearer understanding of where your money is going, you’ll be in a better position to allocate funds toward paying down your balance rather than wasting money on unnecessary purchases.
- Avoiding the Cycle of Credit Card Debt
Credit card debt can quickly become a trap. When you make purchases on credit cards, it feels like you’re not spending real money, and it’s easy to get caught up in the moment. This can lead to high balances, interest charges, and ultimately, financial stress.
Understanding why you spend can help break this cycle. For example, if you tend to overspend when you’re feeling bored or stressed, you might decide to look for healthier ways to cope, like exercising or finding a hobby that doesn’t involve spending money. Alternatively, you might identify a pattern of purchasing things you don’t actually need or use, which could lead you to reconsider your priorities.
Once you have a clearer understanding of your spending habits, you can focus on paying down your credit card debt with more intention. For instance, if you consolidate your debt with a credit card debt consolidation loan, understanding the reasons behind your spending will help you avoid falling back into old habits and racking up new balances. By addressing the root causes of your spending, you’ll be more successful in paying off your debt and avoiding future financial strain.
- Setting Financial Goals and Living Within Your Means
Understanding why you spend money isn’t just about controlling your spending—it’s also about helping you live within your means. Once you know the areas where you tend to overspend, you can start making a plan to spend more intentionally and work toward your financial goals, like saving for retirement or building an emergency fund.
When you’re aware of your spending triggers, it becomes easier to prioritize your financial goals. If you know that you tend to spend more during certain times of the year—like around holidays or after a stressful event—you can plan ahead to account for these periods. Budgeting becomes much more effective when you understand why you spend, as you can create a realistic plan that takes these factors into account.
Living within your means doesn’t mean cutting out all fun or spontaneity. It means being aware of your financial situation and making decisions that align with your goals. It’s about striking a balance between spending for enjoyment and being responsible with your money.
- Developing Healthy Financial Habits
Understanding your spending behavior can be the first step toward developing healthier financial habits. By tracking your expenses and recognizing your emotional triggers, you can create a plan for managing money more effectively.
For example, if you tend to overspend on items you don’t need, you can set a rule for yourself—like waiting 24 hours before making a non-essential purchase. This delay gives you time to think more clearly about whether it’s something you truly want or just an impulse. You can also find alternatives to emotional spending, like taking a walk, reading a book, or talking to a friend instead of reaching for your wallet.
Building better financial habits doesn’t happen overnight, but once you have a clear understanding of why you spend, you can make small, consistent changes that will add up over time. These changes can help you save for long-term goals, pay down debt more efficiently, and ultimately feel more in control of your finances.
- Conclusion: Empower Yourself Through Awareness
Understanding why you spend money is an essential step toward achieving financial stability. It allows you to identify areas of overspending, address emotional triggers, and make more informed financial decisions. Whether you’re working toward paying off debt, saving for retirement, or building an emergency fund, understanding your spending habits will help you get there faster.
By developing financial awareness, you can take charge of your spending and align your choices with your long-term goals. It’s not about restricting yourself—it’s about making intentional, thoughtful decisions that support your financial health. Once you understand why you spend, you’ll have the power to control your money and live within your means, setting yourself up for a brighter, more secure financial future.
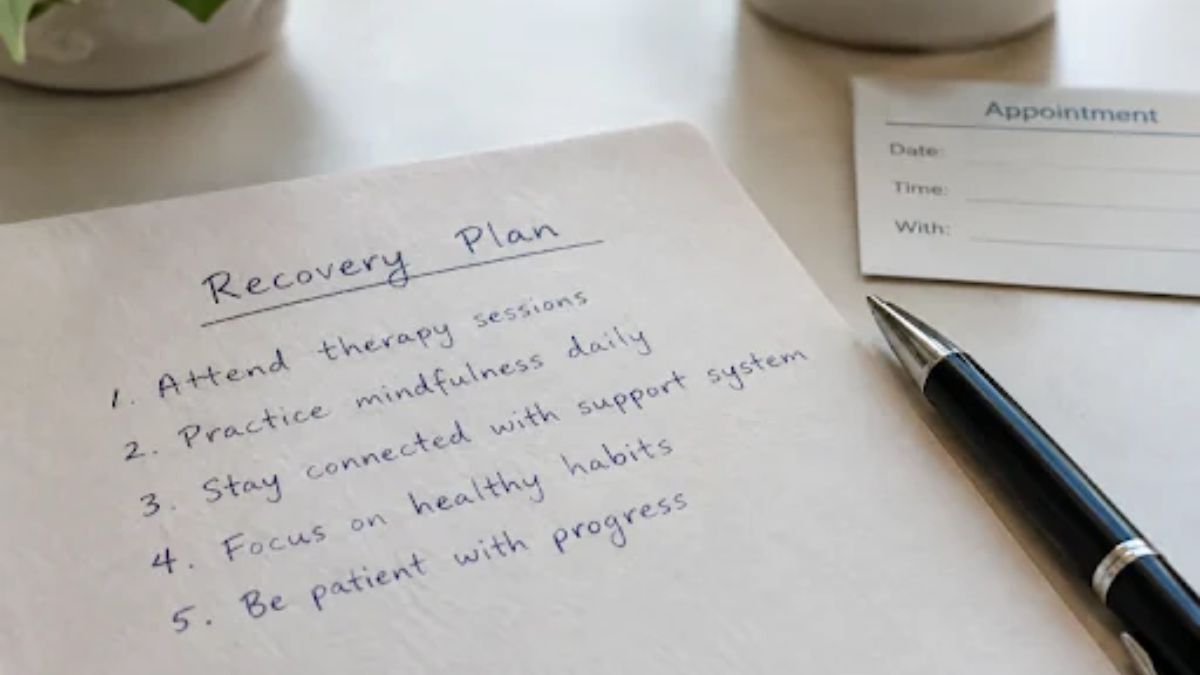
Finishing detox is an important milestone, but it is usually the beginning of the next phase of recovery rather than the end of treatment. For adults who need coordinated follow-up, alcohol addiction treatment services at Desert Mountain Healing IOP combine clinical medication support, counseling, intensive outpatient programming, case management, and recovery planning when appropriate. The Rio Rancho provider serves Albuquerque and surrounding New Mexico communities with an individualized approach that helps connect medical needs with day-to-day recovery goals.
The period after detox can feel both hopeful and uncertain. Physical withdrawal symptoms may improve, yet cravings, stress, relationship problems, mental health concerns, and practical responsibilities can still make recovery difficult. A clear plan creates structure for the days and weeks ahead.
Key Takeaways
- Detox can help a person safely manage withdrawal, but it is generally only the first stage of recovery.
- An effective plan brings together medical follow-up, counseling, routines, and personal support.
- Medication may be appropriate for some people with alcohol or opioid use disorders and should be managed by a qualified clinician.
- Transportation, housing, work schedules, and insurance can affect whether treatment is realistic and accessible.
- Recovery plans should be reviewed regularly and adjusted as circumstances change.
Table Of Contents
- Detox Is Only the First Step
- Build a Care Plan Before Leaving Detox
- Connect Medical and Behavioral Care
- Make Daily Life Work With Treatment
- Plan for Cravings and High-Risk Moments
- Consider Medication Support When Appropriate
- Use Family, Peer, and Community Support
- Review the Plan Over Time
- Common Questions After Detox
Detox Is Only the First Step
Detox focuses on the immediate effects of stopping or reducing substance use, including withdrawal symptoms that may require medical attention. Ongoing treatment addresses a different set of needs: coping with cravings, improving decision-making, treating co-occurring mental health symptoms, repairing relationships, and building a stable routine. As addiction treatment and recovery guidance explains, recovery often involves continuing care and services that support long-term health.
For example, someone may leave detox feeling physically stronger but return to the same stress at home, conflict in a relationship, or social setting connected with past substance use. Planning for those realities can make the transition less overwhelming.
Build a Care Plan Before Leaving Detox
A discharge recommendation is more useful when it becomes a specific, written next step. Before leaving detox, ask what level of care is recommended, when the first appointment will occur, who will manage medications, and what to do if symptoms worsen after regular business hours.
Questions To Answer Before Discharge
- What provider or program will handle follow-up care?
- Has the referral been received and accepted?
- How will transportation to appointments work?
- Are insurance approval, copays, or medication costs likely to create barriers?
- Which records, releases, or prescriptions need to be transferred?
When possible, schedule the first appointment before discharge. Keep the provider’s name, address, phone number, appointment time, and after-hours contact information in one place. With permission, a trusted support person can also keep a copy of the plan.
Connect Medical and Behavioral Care
Recovery can involve both physical and emotional health, so communication among providers matters. Depending on a person’s needs, care may include medical evaluations, medication management, individual counseling, group therapy, intensive outpatient services, case management, mental health screening, family education, and relapse-prevention work.
Coordinated care helps prevent a person from having to manage disconnected recommendations on their own. It also gives the treatment team a clearer view of symptoms, progress, medication concerns, and barriers to participation.
Make Daily Life Work With Treatment
A recovery plan has to fit real life. Work, school, parenting, caregiving, housing, and transportation needs do not disappear after detox. The recovery framework of health, home, purpose, and community can help people consider whether a plan supports the broader conditions needed for stability.
Daily Planning Checklist
- Set consistent times for sleep, meals, prescribed medication, and appointments.
- Arrange transportation before the first treatment session.
- Keep contact numbers and appointment reminders accessible.
- Allow time for work, family responsibilities, rest, and recovery activities.
- Limit avoidable exposure to people, places, or events strongly associated with substance use.
- Build extra time into the schedule for stressful or difficult days.
Plan for Cravings and High-Risk Moments
Cravings and stressful moments are easier to manage when a response plan is already in place. Willpower alone can be difficult to rely on when someone is tired, upset, isolated, or in an environment linked to past use.
Build a Personal Craving Plan
- List common triggers, such as conflict, loneliness, physical pain, payday, or unstructured evenings.
- Identify early warning signs, including skipped appointments, isolation, anger, or racing thoughts.
- Choose one immediate action, such as leaving the situation, contacting a support person, or calling the care team.
- Keep crisis and support numbers easy to find.
- Review the plan with a clinician or trusted person and update it when needed.
Seek urgent medical help for suspected overdose, seizures, severe withdrawal symptoms, serious breathing problems, chest pain, confusion, or immediate thoughts of self-harm.
Consider Medication Support When Appropriate
Medication-assisted treatment is not one medication or a fixed timeline. For some people, prescribed medication may reduce cravings, support stabilization, or help them participate more fully in counseling and recovery services. A qualified prescriber should consider medical history, current symptoms, other medications, treatment goals, and clinical risks.
Medication choice, dose, monitoring, and duration differ from person to person. People should not start, stop, or change prescribed medication without medical guidance. Insurance coverage and local availability may also affect the options a person can access.
Use Family, Peer, and Community Support
Support people can provide practical help without replacing professional care. They may offer transportation, help organize paperwork, provide a calm place to talk, or participate in family education when appropriate. Respect for privacy, boundaries, and treatment goals is essential.
No one person should have to carry the entire recovery plan. A broader network can include clinicians, peer support groups, trusted friends, family members, community programs, and crisis resources.
Review the Plan Over Time
Recovery plans need adjustment. A new job, move, family crisis, medication change, return to substance use, or change in mental health symptoms may call for more support or a different level of care. Missed appointments can also point to practical barriers, such as transportation problems or unstable housing, rather than a lack of commitment.
Monthly Review Questions
- Are appointments and medications accessible?
- Does the current living environment support recovery?
- Are cravings becoming easier or harder to manage?
- Which parts of the plan feel unrealistic?
- What support would make the next month safer?
Common Questions After Detox
Does Finishing Detox Mean Treatment Is Complete?
No. Detox may help stabilize the body, while continuing care can address coping skills, mental health, relationships, routines, and long-term recovery goals.
Can Someone Work While Attending Outpatient Treatment?
Outpatient care may fit around work, school, or family duties. The right schedule depends on clinical needs, stability, transportation, and available support.
What If Substance Use Happens Again?
Contact the treatment team promptly. A return to use may mean the current plan needs additional structure, a new medical assessment, different services, or stronger support.
Conclusion
Detox can open the door to recovery, but the next steps help make recovery safer and more sustainable. A practical plan connects medical care, counseling, routines, support people, and clear responses to difficult moments. The most useful plan is not necessarily the most complicated one. It is the plan a person can understand, access, and adapt as life changes.
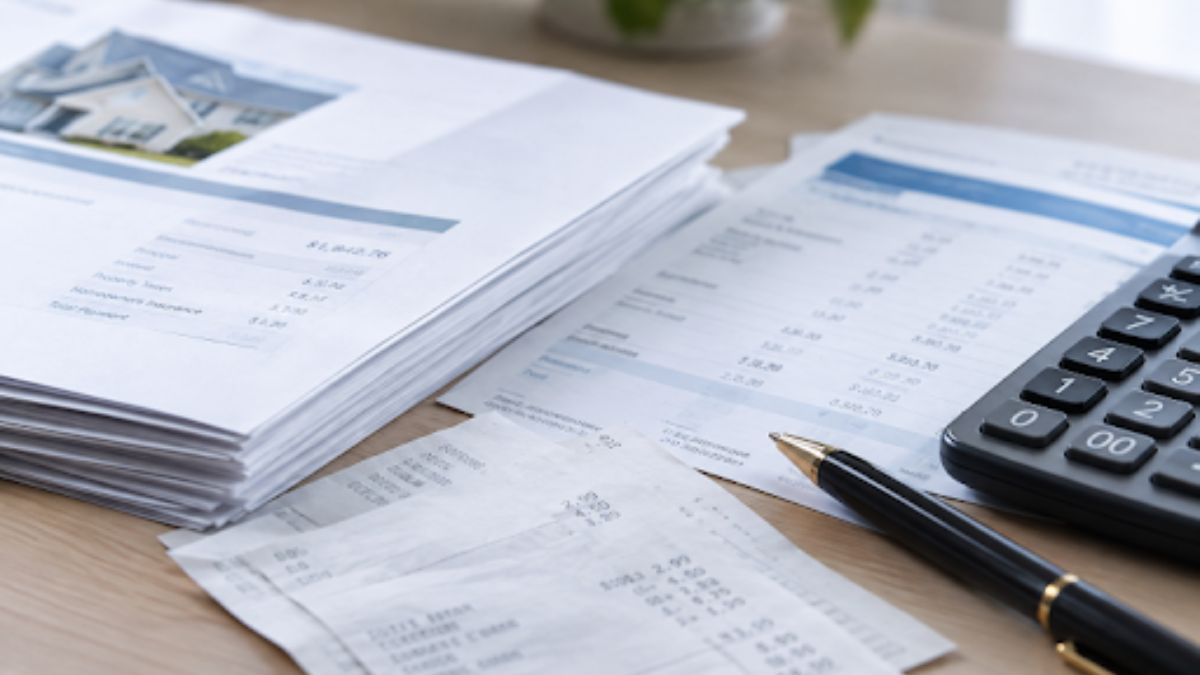
Buying a home can feel out of reach when your financial life does not fit the standard pattern of one employer, regular pay stubs, and a long credit history. Families with contract income, multiple jobs, recent moves, or limited U.S. credit can still take meaningful steps toward becoming stronger applicants. Some borrowers may also explore ITIN mortgage loans when traditional documentation or identification requirements do not reflect their circumstances.
The goal is not to make your finances look different from what they are. It is to organize an accurate, consistent picture of how you earn, spend, save, and pay your obligations. Early preparation can help you identify gaps, answer lenders’ questions more quickly, and make a more confident decision about the price range that fits your household.
Why Financial Records Matter
Mortgage lenders generally assess an applicant’s ability to repay a loan by reviewing income, debts, available funds, credit information, and other application details. A credit score is important, but it does not always tell the full story. For example, a renter may have a reliable history of paying rent on time while having few accounts reported to the major credit bureaus.
Organized records help show the pattern behind the numbers. The Consumer Financial Protection Bureau recommends that buyers prepare by reviewing their credit, assessing their finances, setting a home-price budget, and gathering application materials before shopping for a mortgage. This can make it easier to spot issues before they become a time-sensitive problem.
What Nontraditional Financial History Means
Nontraditional financial history is a practical description of circumstances that may not appear neatly in a conventional mortgage file. It can include a thin credit profile, self-employment, contract work, income from several jobs, a short U.S. credit history, or recurring payments that are not consistently reported on a credit report.
- Self-employment, freelance work, tips, commissions, or seasonal earnings
- Income received through more than one employer or client
- Verified rent, utility, insurance, or phone payments
- Recent relocation or newly established credit accounts
- Documented savings built gradually over time
Documents to Gather Before Applying
Create one secure digital folder and keep paper copies when useful. A lender may request different items depending on the loan and borrower, but a well-organized file can reduce back-and-forth questions.
- Recent bank statements and earnings statements
- Pay stubs, tax returns, tax transcripts, 1099 forms, or business records when applicable
- Invoices, contracts, and payment records for contract or self-employed income
- Rental receipts or a landlord-provided payment history
- Utility, insurance, and other recurring payment records
- Statements for current debts and monthly obligations
- Identification documents and proof of the source of down payment funds
How Alternative Credit May Help
Some lending programs and lenders may review verified payment records beyond standard credit accounts. These records can help demonstrate a pattern of meeting recurring obligations, especially when a borrower has limited traditional credit. They are not a substitute for the full application review, and acceptance varies by lender and loan program.
Records That May Be Useful
- Rent payments made through a traceable method
- Electric, gas, water, internet, or phone bills
- Auto, renters, health, or other insurance payments
- Child care, tuition, or similar recurring obligations
Keep records that clearly identify the account holder, the payment amount, the due date, and the payment date. Cash payments can be difficult to verify without receipts, bank withdrawals, or a written payment history from the recipient.
How to Organize Different Income Sources
Families with multiple income sources should make the connection between the work performed and the money received easy to follow. A contractor, for example, can keep invoices, signed agreements, deposit records, and tax documents together to show how business income is deposited into a personal account.
- List every household income source and how often it is paid.
- Separate business and personal transactions when possible.
- Keep invoices, contracts, and deposit records in date order.
- Be ready to explain large or unusual deposits.
- Avoid moving money between accounts without retaining a clear paper trail.
How to Build a Realistic Homebuying Budget
The amount a lender may approve is not always the amount that feels comfortable for your family. Build your budget around the full monthly housing cost, including principal and interest, property taxes, homeowners’ insurance, mortgage insurance if required, homeowners’ association dues if applicable, utilities, and expected maintenance.
Also plan for upfront costs such as the down payment, closing costs, moving expenses, and immediate repairs or purchases. Review several months of actual spending before setting a target payment. The CFPB advises buyers to compare mortgage offers from multiple lenders, which can help households evaluate loan terms and costs rather than focusing on one advertised rate. This gives buyers a practical framework for that process.
Questions to Ask a Mortgage Professional
- Which documents can be used to verify my income?
- Can verified rent or utility payments be considered in this program?
- How much payment history is needed?
- How are self-employed, contract, commission, or seasonal earnings reviewed?
- Which funds may be used for the down payment and closing costs?
- What fees are due before closing, and what costs are included in the estimate?
- Would a co-borrower change the available options?
Mistakes That Can Slow Down an Application
- Applying before checking credit reports for errors or missing information
- Leaving large deposits unexplained
- Taking on new debt or opening unnecessary credit accounts before closing
- Changing jobs or income structure without discussing it with the lender
- Using cash without maintaining receipts or other documentation
- Underestimating taxes, insurance, repairs, and moving costs
A Step-by-Step Preparation Plan
- Set a price range. Base it on the full monthly cost and your household budget.
- Review credit and debts. Correct errors and understand existing monthly obligations.
- Build a document folder. Save bank, income, tax, rent, and payment records in one place.
- Track savings. Keep a clear record of where the down payment and closing funds come from.
- Speak with qualified lenders. Ask how each one reviews your specific financial records.
- Keep records current. Continue documenting income, payments, and account activity through closing.
Final Thoughts
Homeownership preparation is not limited to households with a long, conventional credit history. Clear records, steady financial habits, realistic budgeting, and early conversations with mortgage professionals can help families present a more complete application. Start by organizing the facts, protecting your savings, and choosing a home payment that supports your life after closing.
HOME
How to Plan Laser Hair Removal Around Skin Tone, Hair Growth, and Seasonal Sun Exposure in Centennial, Colorado
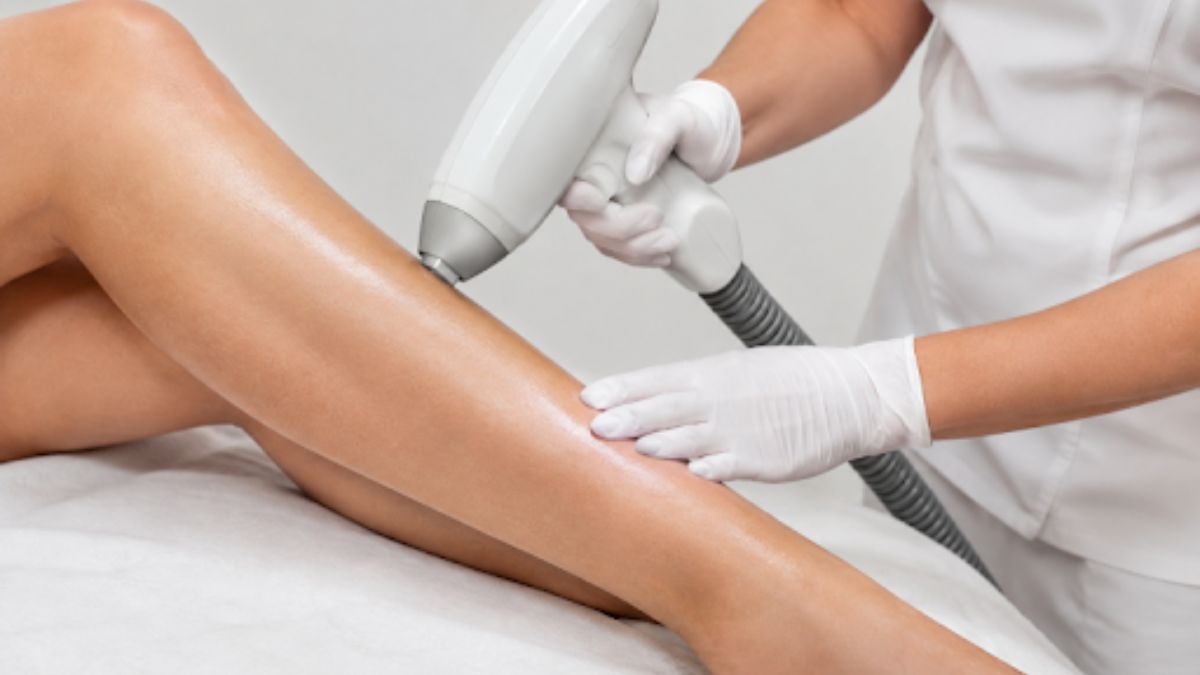
Planning laser hair removal in Centennial, Colorado, involves more than choosing a convenient appointment date. The timing should account for your hair growth pattern, your skin’s current condition, and how much sun exposure is likely during work, recreation, travel, and daily life along the Front Range.
For local clients comparing options, Hair To Bare South offers laser hair removal services Centennial, CO with treatment options organized by small, medium, large, and extra-large areas. Its service information helps Centennial-area clients understand the range of areas that may be treated and why a consistent, safety-focused plan matters when working toward long-term hair reduction.
Why Treatment Timing Matters
Laser hair removal is not typically a one-visit solution. The laser is designed to target pigment associated with the hair and follicle, but only some follicles are in the most responsive stage at a given time. That is why appointments are commonly spread across a series rather than scheduled back-to-back.
According to the American Academy of Dermatology’s laser hair removal guidance, many patients can be treated about every four to six weeks, although the appropriate interval depends on the person and area treated. A provider should set the schedule based on visible regrowth, skin response, and treatment goals.
How the Hair Growth Cycle Affects Results
Hair moves through several broad growth phases. Understanding them can make the treatment process feel less mysterious.
Active growth
During the active growth stage, often called anagen, the follicle has a stronger connection to the hair being treated. This is generally the stage in which laser treatment is most useful.
Transition and resting
In the transition stage, growth slows. In the resting stage, the follicle does not produce a new visible hair in the same way. Since neighboring follicles can be in different phases, one session cannot address every hair at once.
Consistency is more valuable than rushing. Scheduling too frequently does not necessarily create faster results, while long, irregular gaps can make it harder to follow a clear plan for recurring growth.
Skin Tone, Hair Color, and Hair Texture
Darker, coarser hair often provides a clearer target because it contains more pigment. Fine blonde, gray, white, and some red hair can be more difficult for laser-based treatment to detect and reduce. That does not mean a consultation is pointless, but it does mean expectations should be discussed honestly before treatment begins.
People with darker skin tones may be candidates for laser hair removal, but device selection, settings, and provider experience become especially important. Ask how the provider evaluates skin coloring and how they reduce the risk of burns, irritation, or unwanted pigment changes. A careful consultation should never treat skin tone or hair type as an afterthought.
Seasonal Planning for Centennial Sun Exposure
There is no single best season for every person, but Centennial’s bright weather and outdoor lifestyle can affect the practical side of planning. Ski days, patio time, hikes, golf, and warm-weather trips can all increase sun exposure, including when temperatures feel cool.
- Winter: Less exposed skin and fewer tanning opportunities may make aftercare easier for some people.
- Spring: Starting early can provide time for a series of sessions before summer activities become frequent.
- Summer: Treatment may still be possible, but it requires careful communication about recent sun, tanning, and travel plans.
- Fall: This can be a practical point to begin or resume a treatment series after a more sun-intensive season.
The importance of planning ahead for warmer weather is especially relevant when you expect pool days, vacations, or prolonged outdoor events. Recent tanning, including indoor tanning and self-tanning products, should be disclosed so the provider can determine whether treatment should proceed or be postponed.
Why Treatment Area Changes the Timeline
Small areas such as the upper lip, chin, or underarms can take less appointment time than the legs, back, or chest. However, a shorter appointment does not always mean a shorter overall course of treatment. Hair density, thickness, and hormonal influence can vary substantially from one body area to another.
For example, someone may notice meaningful changes in underarm hair before seeing the same degree of reduction on the legs. Facial hair can require added patience because it may be finer or influenced by hormonal changes. Maintenance visits may be useful for some people after the initial series, particularly when new growth develops over time.
Simple Steps to Prepare
- Avoid tanning and follow the provider’s instructions about sun exposure.
- Share medications, skin conditions, recent cosmetic procedures, and any history of unusual scarring.
- Ask whether shaving is recommended before your appointment.
- Avoid waxing, plucking, or epilating when the provider advises leaving the follicle intact.
- Arrive with clean skin and avoid products that may irritate the treatment area.
- Wear soft, comfortable clothing that will not rub against freshly treated skin.
Questions to Ask Before Booking
- What experience do you have with my skin tone and hair type?
- Which laser or light-based device will you use?
- How many appointments may be appropriate for this area?
- How far apart should my sessions be scheduled?
- What should I avoid before and after each appointment?
- Which side effects are expected, and which require follow-up?
- Would a consultation or test spot be appropriate?
Realistic Results and Long-Term Planning
It is more accurate to think in terms of permanent hair reduction than guaranteed removal of every hair forever. Results differ by skin tone, hair characteristics, hormonal changes, area treated, device, and appointment consistency. A trustworthy provider explains those variables clearly instead of promising identical results for everyone.
A strong consultation includes a review of recent sun exposure, a plain-language timeline, discussion of possible side effects, and a plan tailored to the individual. In Centennial, the best laser hair removal schedule is usually the one that protects your skin, fits your calendar, and gives each treatment enough time to work.
-
 HEALTH2 years ago
Integrating Semaglutide into Your Weight Loss Plan: A Practical Guide
-
 HOME IMPROVEMENT2 years ago
How to Choose the Perfect Neutral Area Rug for Every Room
-
 FASHION2 years ago
7 Celebrity-Inspired Elegant Summer Dresses For 2024
-
 HOME2 years ago
Sandra Orlow: The Teen Model Who Captivated the Internet
-
 LAW2 years ago
Teenage Drivers and Car Accidents in California: Risks and Parental Liability
-
 CONSTRUCTION2 years ago
Construction Site Safety Regulations in New York and Your Rights as a Worker
-
 LAW2 years ago
Post-Divorce Considerations in California: Modifications and Long-Term Planning
-
 FINANCE2 years ago
Digital Asset Management in Florida Estate Planning