HOME
Carter Belfort: Charting His Own Path Beyond the Shadow of Fame

The name Belfort is synonymous with Wall Street, extravagant wealth, and a notorious reputation captured in popular media. But beyond the glitz and the scandal lies a new chapter—one that doesn’t revolve around the infamous Jordan Belfort, but his son, Carter. This blog post explores Carter Belfort’s unique path as he strives to carve out his own place in the world, distinct from his father’s shadow. We’ll explore his endeavors, challenges, and ambitions, providing insights into his life beyond the headlines.
Understanding the Carter Belfort Legacy
Before we discuss Carter Belfort story, it’s essential to understand the weight of the Belfort name. Jordan Belfort, often referred to as the “Wolf of Wall Street,” made headlines for both his financial prowess and his legal troubles. His life was famously depicted in the movie starring Leonardo DiCaprio, portraying a world of luxury, ambition, and eventual downfall. This legacy, while captivating, brings its own set of challenges to anyone connected to it, especially family members.
Growing up with such a last name means inheriting public perceptions, expectations, and pressures. For Carter, this meant navigating a world where opinions were formed long before any personal interaction. His task wasn’t just to make a name for himself but to redefine what it means to be a Belfort in the contemporary world. This required resilience, vision, and an unwavering commitment to authenticity.
The story of Carter Belfort isn’t just about overcoming a name; it’s about understanding the multifaceted nature of legacy. It’s about recognizing both the burdens and opportunities it presents and finding a way to honor the past while forging a new path forward. This delicate balance defines the starting point of Carter’s unique narrative.
Early Influences and Aspirations
Carter Belfort’s early life was a mix of privilege and public scrutiny. Growing up in an environment influenced by wealth and notoriety, he was exposed to both the advantages and the pitfalls of fame from a young age. These experiences shaped his worldview and played a crucial role in his evolving aspirations.
From an early age, Carter displayed a keen interest in business, much like his father. However, he was determined to approach it differently. Rather than focusing solely on financial gain, Carter was interested in creating something meaningful, something that could stand the test of time without controversy. He was passionate about building a legacy based on innovation, ethics, and impact.
Beyond business, Carter’s upbringing instilled in him a love for creativity and expression. He explored this interest through music and writing, using these platforms to share his perspectives and connect with others. These creative pursuits provided an avenue for Carter to express himself freely, unencumbered by the expectations associated with his last name.
Education as a Foundation
For Carter, education was more than a stepping stone; it was a foundation for growth and exploration. He recognized early on that knowledge and skills could empower him to achieve his goals independently of his family name. This understanding drove him to pursue higher education passionately.
Carter’s academic journey was marked by a commitment to learning and personal development. He sought out opportunities that would challenge him intellectually and push him outside his comfort zone. This approach allowed him to gain a diverse skill set and a broader perspective on the world around him.
Through education, Carter learned the importance of critical thinking, collaboration, and persistence. These lessons became invaluable as he navigated the complexities of carving out his path. Education provided him with the tools to dream big and the confidence to act on those dreams.
Entering the Business World
Armed with education and ambition, Carter entered the business world determined to make his mark. Unlike his father, he was committed to doing so with integrity and transparency. He understood that building a reputation based on trust and accountability was crucial to his long-term success.
Carter’s approach to business was characterized by innovation and adaptability. He sought to identify emerging trends and opportunities, leveraging technology and creativity to stay ahead of the curve. This forward-thinking mindset set him apart in a competitive landscape and positioned him for success.
Throughout his early career, Carter faced numerous challenges and setbacks. However, he viewed these obstacles as learning opportunities rather than failures. This resilience and determination enabled him to persevere and continue building his business ventures with confidence and clarity.
The Role of Mentorship
Mentorship played a significant role in Carter’s development as a business leader. He actively sought guidance from experienced professionals who could offer insights and support as he navigated his career. These mentors provided valuable feedback, encouragement, and perspectives that helped shape Carter’s decision-making and leadership style.
Through mentorship, Carter learned the importance of humility and openness to feedback. He understood that there was always room for growth and improvement, regardless of one’s achievements. This mindset allowed him to remain grounded and focused on continuous learning.
Additionally, Carter recognized the value of paying it forward. He became a mentor to others, sharing his experiences and insights with aspiring entrepreneurs. This commitment to mentorship reinforced his dedication to making a positive impact and contributing to the success of others.
Pursuing Creative Passions
While business was an important part of Carter’s identity, he never lost sight of his creative passions. Music and writing remained a vital outlet for self-expression and connection. Through these mediums, Carter explored themes of resilience, ambition, and authenticity, resonating with audiences who shared similar experiences.
Carter’s creative endeavors provided a sense of balance and fulfillment, complementing his business pursuits. They allowed him to explore different facets of his identity and share his unique voice with the world. This integration of creativity and entrepreneurship became a defining characteristic of Carter’s personal brand.
By pursuing his creative passions, Carter demonstrated that success could be multifaceted and inclusive of different interests. He showed that it was possible to excel in business while remaining true to one’s artistic inclinations. This holistic approach to life and career resonated with many young professionals seeking to balance their diverse passions.
Building a Personal Brand
In today’s digital age, personal branding is a powerful tool for differentiation and influence. Carter recognized the importance of building a personal brand that reflected his values, ambitions, and unique story. He leveraged social media and content creation to share his insights and connect with a global audience.
Carter’s personal brand was rooted in authenticity and transparency. He was open about his challenges and successes, using his platform to inspire and motivate others. This honesty and relatability resonated with his audience, fostering a sense of community and trust.
Through his personal brand, Carter demonstrated the value of consistency and intentionality. He curated content that aligned with his goals and aspirations, reinforcing his commitment to ethical business practices and creative expression. This strategic approach allowed him to stand out in a crowded digital landscape and build meaningful relationships.
Navigating Challenges and Setbacks
Every entrepreneurial journey is fraught with challenges and setbacks, and Carter’s was no exception. However, he approached these obstacles with resilience and a growth mindset, viewing them as opportunities for learning and development.
Carter’s ability to adapt and pivot in the face of adversity was a testament to his determination and perseverance. He understood that setbacks were a natural part of the entrepreneurial process and remained focused on his long-term vision.
Throughout his career, Carter learned the importance of balancing short-term challenges with long-term goals. This perspective allowed him to maintain clarity and purpose, even in the face of uncertainty. By staying true to his values and principles, he continued to move forward with confidence and determination.
The Power of Community
Community played a central role in Carter’s personal and professional life. He understood that success was not achieved in isolation and actively sought to build and nurture connections with like-minded individuals. This sense of community provided support, encouragement, and accountability, enabling Carter to thrive.
Through networking and collaboration, Carter expanded his reach and impact. He engaged with diverse perspectives and ideas, fostering innovation and creativity in his work. This commitment to collaboration demonstrated the value of leveraging collective strengths for shared success.
Carter’s dedication to community extended beyond business. He actively contributed to social causes and initiatives, using his platform to raise awareness and drive positive change. This commitment to giving back reinforced his role as a conscientious and responsible leader, inspiring others to do the same.
Looking Towards the Future
Carter Belfort’s journey is a testament to the power of resilience, authenticity, and vision. He has demonstrated that it is possible to build a successful and meaningful career while honoring one’s values and passions. His story serves as an inspiration to aspiring entrepreneurs seeking to create their path in the world.
Looking towards the future, Carter remains committed to innovation and impact. He continues to explore new opportunities and challenges, driven by a desire to make a positive difference. By staying true to his values and principles, he is well-positioned to continue building a legacy that transcends his family name.
Carter’s story is a reminder that success is not defined by circumstances but by choices and actions. It is a call to action for individuals to pursue their dreams with integrity and purpose, knowing that they have the power to create a future that reflects their unique identities and aspirations.
Conclusion
Carter Belfort’s story is one of transformation and empowerment. It is a narrative of breaking free from the past and charting a new course toward a future defined by purpose and authenticity. His journey exemplifies the potential of individuals to create meaningful change and leave a lasting impact.
For those inspired by Carter’s example, the takeaway is clear: pursue your passions with conviction, honor your values, and build a legacy that reflects who you are. By doing so, you have the power to redefine what it means to be successful and leave your mark on the world.
Buying a home can feel out of reach when your financial life does not fit the standard pattern of one employer, regular pay stubs, and a long credit history. Families with contract income, multiple jobs, recent moves, or limited U.S. credit can still take meaningful steps toward becoming stronger applicants. Some borrowers may also explore ITIN mortgage loans when traditional documentation or identification requirements do not reflect their circumstances.
The goal is not to make your finances look different from what they are. It is to organize an accurate, consistent picture of how you earn, spend, save, and pay your obligations. Early preparation can help you identify gaps, answer lenders’ questions more quickly, and make a more confident decision about the price range that fits your household.
Why Financial Records Matter
Mortgage lenders generally assess an applicant’s ability to repay a loan by reviewing income, debts, available funds, credit information, and other application details. A credit score is important, but it does not always tell the full story. For example, a renter may have a reliable history of paying rent on time while having few accounts reported to the major credit bureaus.
Organized records help show the pattern behind the numbers. The Consumer Financial Protection Bureau recommends that buyers prepare by reviewing their credit, assessing their finances, setting a home-price budget, and gathering application materials before shopping for a mortgage. This can make it easier to spot issues before they become a time-sensitive problem.
What Nontraditional Financial History Means
Nontraditional financial history is a practical description of circumstances that may not appear neatly in a conventional mortgage file. It can include a thin credit profile, self-employment, contract work, income from several jobs, a short U.S. credit history, or recurring payments that are not consistently reported on a credit report.
- Self-employment, freelance work, tips, commissions, or seasonal earnings
- Income received through more than one employer or client
- Verified rent, utility, insurance, or phone payments
- Recent relocation or newly established credit accounts
- Documented savings built gradually over time
Documents to Gather Before Applying
Create one secure digital folder and keep paper copies when useful. A lender may request different items depending on the loan and borrower, but a well-organized file can reduce back-and-forth questions.
- Recent bank statements and earnings statements
- Pay stubs, tax returns, tax transcripts, 1099 forms, or business records when applicable
- Invoices, contracts, and payment records for contract or self-employed income
- Rental receipts or a landlord-provided payment history
- Utility, insurance, and other recurring payment records
- Statements for current debts and monthly obligations
- Identification documents and proof of the source of down payment funds
How Alternative Credit May Help
Some lending programs and lenders may review verified payment records beyond standard credit accounts. These records can help demonstrate a pattern of meeting recurring obligations, especially when a borrower has limited traditional credit. They are not a substitute for the full application review, and acceptance varies by lender and loan program.
Records That May Be Useful
- Rent payments made through a traceable method
- Electric, gas, water, internet, or phone bills
- Auto, renters, health, or other insurance payments
- Child care, tuition, or similar recurring obligations
Keep records that clearly identify the account holder, the payment amount, the due date, and the payment date. Cash payments can be difficult to verify without receipts, bank withdrawals, or a written payment history from the recipient.
How to Organize Different Income Sources
Families with multiple income sources should make the connection between the work performed and the money received easy to follow. A contractor, for example, can keep invoices, signed agreements, deposit records, and tax documents together to show how business income is deposited into a personal account.
- List every household income source and how often it is paid.
- Separate business and personal transactions when possible.
- Keep invoices, contracts, and deposit records in date order.
- Be ready to explain large or unusual deposits.
- Avoid moving money between accounts without retaining a clear paper trail.
How to Build a Realistic Homebuying Budget
The amount a lender may approve is not always the amount that feels comfortable for your family. Build your budget around the full monthly housing cost, including principal and interest, property taxes, homeowners’ insurance, mortgage insurance if required, homeowners’ association dues if applicable, utilities, and expected maintenance.
Also plan for upfront costs such as the down payment, closing costs, moving expenses, and immediate repairs or purchases. Review several months of actual spending before setting a target payment. The CFPB advises buyers to compare mortgage offers from multiple lenders, which can help households evaluate loan terms and costs rather than focusing on one advertised rate. This gives buyers a practical framework for that process.
Questions to Ask a Mortgage Professional
- Which documents can be used to verify my income?
- Can verified rent or utility payments be considered in this program?
- How much payment history is needed?
- How are self-employed, contract, commission, or seasonal earnings reviewed?
- Which funds may be used for the down payment and closing costs?
- What fees are due before closing, and what costs are included in the estimate?
- Would a co-borrower change the available options?
Mistakes That Can Slow Down an Application
- Applying before checking credit reports for errors or missing information
- Leaving large deposits unexplained
- Taking on new debt or opening unnecessary credit accounts before closing
- Changing jobs or income structure without discussing it with the lender
- Using cash without maintaining receipts or other documentation
- Underestimating taxes, insurance, repairs, and moving costs
A Step-by-Step Preparation Plan
- Set a price range. Base it on the full monthly cost and your household budget.
- Review credit and debts. Correct errors and understand existing monthly obligations.
- Build a document folder. Save bank, income, tax, rent, and payment records in one place.
- Track savings. Keep a clear record of where the down payment and closing funds come from.
- Speak with qualified lenders. Ask how each one reviews your specific financial records.
- Keep records current. Continue documenting income, payments, and account activity through closing.
Final Thoughts
Homeownership preparation is not limited to households with a long, conventional credit history. Clear records, steady financial habits, realistic budgeting, and early conversations with mortgage professionals can help families present a more complete application. Start by organizing the facts, protecting your savings, and choosing a home payment that supports your life after closing.
HOME
How to Plan Laser Hair Removal Around Skin Tone, Hair Growth, and Seasonal Sun Exposure in Centennial, Colorado

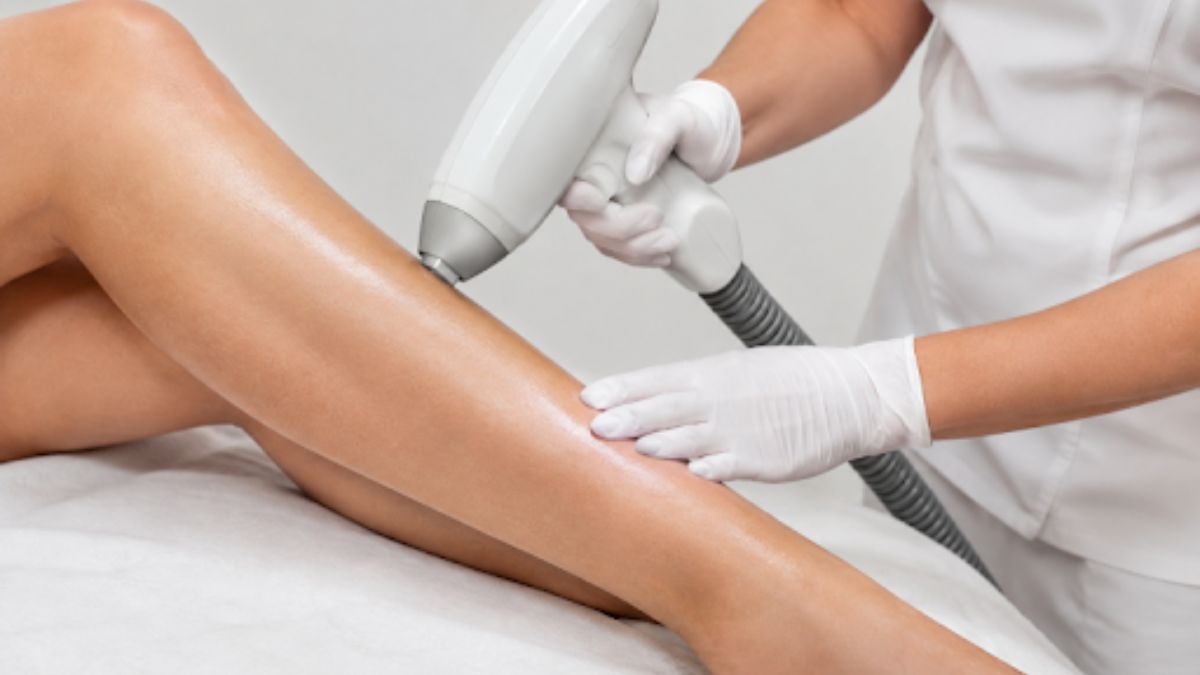
Planning laser hair removal in Centennial, Colorado, involves more than choosing a convenient appointment date. The timing should account for your hair growth pattern, your skin’s current condition, and how much sun exposure is likely during work, recreation, travel, and daily life along the Front Range.
For local clients comparing options, Hair To Bare South offers laser hair removal services Centennial, CO with treatment options organized by small, medium, large, and extra-large areas. Its service information helps Centennial-area clients understand the range of areas that may be treated and why a consistent, safety-focused plan matters when working toward long-term hair reduction.
Why Treatment Timing Matters
Laser hair removal is not typically a one-visit solution. The laser is designed to target pigment associated with the hair and follicle, but only some follicles are in the most responsive stage at a given time. That is why appointments are commonly spread across a series rather than scheduled back-to-back.
According to the American Academy of Dermatology’s laser hair removal guidance, many patients can be treated about every four to six weeks, although the appropriate interval depends on the person and area treated. A provider should set the schedule based on visible regrowth, skin response, and treatment goals.
How the Hair Growth Cycle Affects Results
Hair moves through several broad growth phases. Understanding them can make the treatment process feel less mysterious.
Active growth
During the active growth stage, often called anagen, the follicle has a stronger connection to the hair being treated. This is generally the stage in which laser treatment is most useful.
Transition and resting
In the transition stage, growth slows. In the resting stage, the follicle does not produce a new visible hair in the same way. Since neighboring follicles can be in different phases, one session cannot address every hair at once.
Consistency is more valuable than rushing. Scheduling too frequently does not necessarily create faster results, while long, irregular gaps can make it harder to follow a clear plan for recurring growth.
Skin Tone, Hair Color, and Hair Texture
Darker, coarser hair often provides a clearer target because it contains more pigment. Fine blonde, gray, white, and some red hair can be more difficult for laser-based treatment to detect and reduce. That does not mean a consultation is pointless, but it does mean expectations should be discussed honestly before treatment begins.
People with darker skin tones may be candidates for laser hair removal, but device selection, settings, and provider experience become especially important. Ask how the provider evaluates skin coloring and how they reduce the risk of burns, irritation, or unwanted pigment changes. A careful consultation should never treat skin tone or hair type as an afterthought.
Seasonal Planning for Centennial Sun Exposure
There is no single best season for every person, but Centennial’s bright weather and outdoor lifestyle can affect the practical side of planning. Ski days, patio time, hikes, golf, and warm-weather trips can all increase sun exposure, including when temperatures feel cool.
- Winter: Less exposed skin and fewer tanning opportunities may make aftercare easier for some people.
- Spring: Starting early can provide time for a series of sessions before summer activities become frequent.
- Summer: Treatment may still be possible, but it requires careful communication about recent sun, tanning, and travel plans.
- Fall: This can be a practical point to begin or resume a treatment series after a more sun-intensive season.
The importance of planning ahead for warmer weather is especially relevant when you expect pool days, vacations, or prolonged outdoor events. Recent tanning, including indoor tanning and self-tanning products, should be disclosed so the provider can determine whether treatment should proceed or be postponed.
Why Treatment Area Changes the Timeline
Small areas such as the upper lip, chin, or underarms can take less appointment time than the legs, back, or chest. However, a shorter appointment does not always mean a shorter overall course of treatment. Hair density, thickness, and hormonal influence can vary substantially from one body area to another.
For example, someone may notice meaningful changes in underarm hair before seeing the same degree of reduction on the legs. Facial hair can require added patience because it may be finer or influenced by hormonal changes. Maintenance visits may be useful for some people after the initial series, particularly when new growth develops over time.
Simple Steps to Prepare
- Avoid tanning and follow the provider’s instructions about sun exposure.
- Share medications, skin conditions, recent cosmetic procedures, and any history of unusual scarring.
- Ask whether shaving is recommended before your appointment.
- Avoid waxing, plucking, or epilating when the provider advises leaving the follicle intact.
- Arrive with clean skin and avoid products that may irritate the treatment area.
- Wear soft, comfortable clothing that will not rub against freshly treated skin.
Questions to Ask Before Booking
- What experience do you have with my skin tone and hair type?
- Which laser or light-based device will you use?
- How many appointments may be appropriate for this area?
- How far apart should my sessions be scheduled?
- What should I avoid before and after each appointment?
- Which side effects are expected, and which require follow-up?
- Would a consultation or test spot be appropriate?
Realistic Results and Long-Term Planning
It is more accurate to think in terms of permanent hair reduction than guaranteed removal of every hair forever. Results differ by skin tone, hair characteristics, hormonal changes, area treated, device, and appointment consistency. A trustworthy provider explains those variables clearly instead of promising identical results for everyone.
A strong consultation includes a review of recent sun exposure, a plain-language timeline, discussion of possible side effects, and a plan tailored to the individual. In Centennial, the best laser hair removal schedule is usually the one that protects your skin, fits your calendar, and gives each treatment enough time to work.
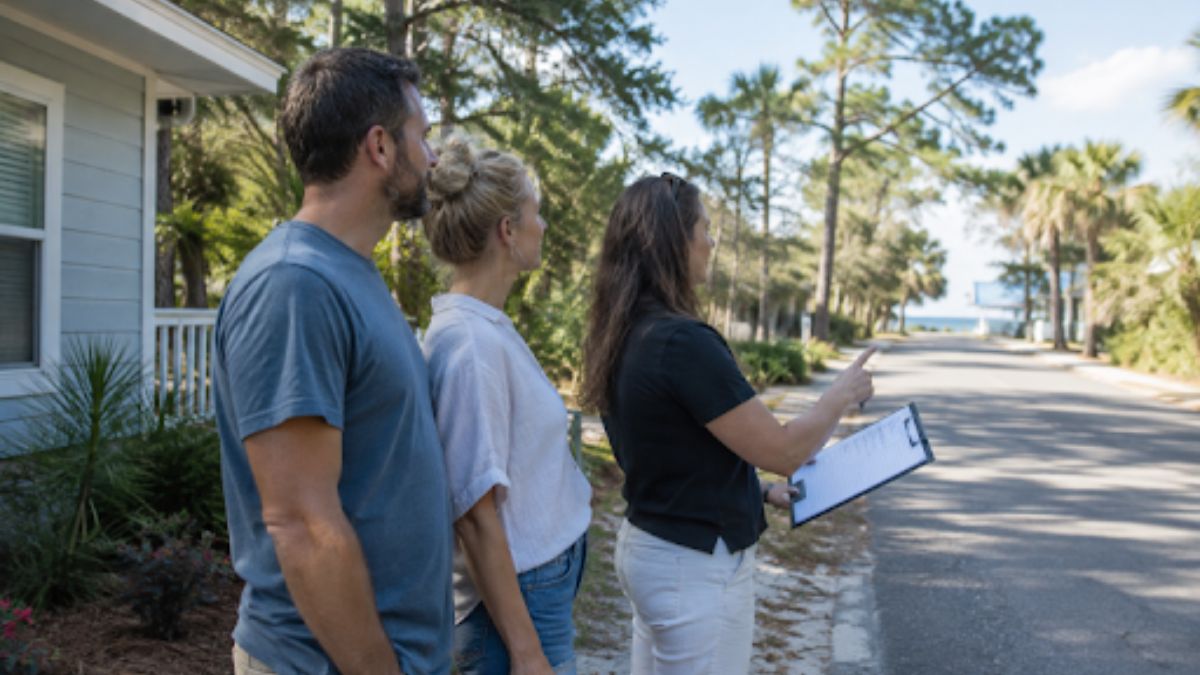
Buying near the water in Pensacola, Florida, can mean very different things depending on whether you picture a downtown-adjacent neighborhood, a Gulf Breeze home near the bay, a quieter Navarre address, or a beach property with sand and water views close by. The best choice is usually not the community with the lowest list price or the shortest walk to the shore. It is the one that fits your budget, routines, risk tolerance, and long-term plans.
For help sorting through those differences, Pensacola real estate agents Coastal Collective Group offers buyer, relocation, waterfront, luxury, and investment-property guidance across Greater Pensacola. Coastal Collective Group is a local real estate team serving Pensacola, Gulf Breeze, Navarre, Pensacola Beach, and Navarre Beach, making it a useful starting point for buyers who need neighborhood-level insight rather than a one-size-fits-all coastal search.
Why the Community Matters as Much as the Home
Two homes with similar prices can create very different ownership experiences. A larger inland home may provide more storage, yard space, and easier access to everyday errands. A smaller beach-area condo may offer views and recreation, but also add association obligations, seasonal activity, and building-level maintenance considerations. The goal is to compare ordinary weekdays, storm preparation, and long-term upkeep, not just a sunny weekend showing.
Start With the Property’s Main Job
- Primary residence: Prioritize work routes, healthcare, schools, groceries, and year-round services.
- Second home: Look for practical lock-and-leave features, manageable maintenance, and convenient arrival routes.
- Vacation rental: Review local requirements, association rules, rental limits, and realistic operating expenses before relying on projected income.
- Investment property: Consider demand, vacancies, repairs, taxes, financing, and the resale market for comparable homes.
- Retirement home: Evaluate access to medical care, home layout, walkability, storm readiness, and ongoing upkeep.
Compare Pensacola-Area Communities by Lifestyle
Pensacola
Pensacola can suit buyers who want a wider range of housing styles and access to downtown, employment centers, restaurants, healthcare, shopping, and airport travel. The city includes established neighborhoods, historic areas, newer developments, and waterfront-adjacent options, so buyers should compare individual neighborhoods rather than treating Pensacola as a single, uniform market.
Gulf Breeze
Gulf Breeze appeals to buyers seeking a primarily residential setting with access to Pensacola and nearby beach areas. Test important routes at the times you would actually use them, especially when bridge access affects the trip. For each property, examine lot drainage, flood information, insurance estimates, nearby services, and the practical distance to work or school.
Navarre
Navarre offers a different pace, with mainland neighborhoods, newer homes, and beach access. Carefully compare mainland Navarre with Navarre Beach. A home may be close to the water yet have a very different commute, lot size, insurance profile, rental environment, and availability of everyday services than another property only a few miles away.
Pensacola Beach and Navarre Beach
These beach communities offer direct coastal recreation, water views, and a distinct vacation-oriented atmosphere. They also require close attention to storm exposure, wind and flood insurance, seasonal traffic, shared-building responsibilities, and ownership structure. With a condo or townhome, request the association budget, reserve information, rules, insurance details, meeting minutes, and any information about pending assessments.
Build a Realistic Total-Cost Estimate
Your purchase price is only one part of the decision. Create monthly and annual estimates that include the mortgage, property taxes, homeowners’ insurance, flood coverage when applicable, HOA or condo fees, utilities, maintenance, and travel costs. For waterfront homes, also consider exterior materials, roofs, docks, seawalls, pools, landscaping, and marine-related maintenance. Request insurance quotes for the exact address, because roof age, construction, elevation, and prior claims can affect cost.
Check Flood Exposure and Coastal Risk
Flood risk should be reviewed at the address level, rather than assumed based on a neighborhood name or a nearby property. Use the FEMA Flood Map Service Center to review the property’s mapped flood information, then ask for available elevation documentation and seller disclosures. During inspections, look closely at drainage, roof condition, windows, doors, foundation type, and storm-protection features. A lower-risk map designation does not mean flooding is impossible, so buyers should still consider drainage patterns, coverage options, and their own financial comfort level.
Review Commutes and Everyday Access
Drive key routes during morning and afternoon work periods, weekends, and a busy beach-season day when possible. Check the trip to work, schools, hospitals, pharmacies, grocery stores, military facilities, and the airport. Online map estimates are useful, but they cannot fully show how a route feels during a real errand run or after an event. Confirm school assignments directly with the appropriate district because boundaries and enrollment policies can change.
Match the Property Type to Your Lifestyle
- Single-family homes: Often provide privacy, storage, parking, and yard space. Review drainage, trees, fencing, exterior materials, roof age, and storm preparedness.
- Condos and townhomes: Can reduce personal exterior maintenance, but buyers should understand fees, rules, insurance responsibilities, parking, pets, rentals, reserves, and assessments.
- Waterfront homes: Require careful review of docks, lifts, seawalls, erosion, water depth, access, permits, and maintenance responsibilities. Waterfront does not automatically mean the same boating access or insurance profile.
Use Local Data, Not Broad Headlines
National real estate headlines rarely accurately describe every segment of the Pensacola area. Compare recent closed sales, active listings, pending properties, and days on market for homes that closely match the property type, location, condition, and amenities you are considering. Beach condos, inland family homes, luxury residences, and rental-oriented properties can behave differently, even within the same broader area.
Questions to Ask Before Making an Offer
- What will the total monthly ownership cost be after insurance, fees, taxes, and maintenance?
- Is flood insurance required, available, recommended, or excluded from the current quote?
- What repairs or replacements may be needed within the next five years?
- Do HOA rules affect rentals, renovations, pets, boats, parking, or exterior changes?
- Are there any planned changes to roads, drainage, construction, or development nearby?
- Which recent sales are the most relevant comparisons for this specific home?
A Simple Community Comparison Worksheet
Score each community from one to five, then write a few notes beside every category:
- Purchase price: Compare similar homes, not broad averages.
- Insurance and flood exposure: Use quotes and documents tied to the specific address.
- Commute and access: Test important routes during busy periods.
- Daily lifestyle: Consider quiet time, recreation, restaurants, parks, and errands.
- Maintenance needs: Include roofs, pools, yards, docks, seawalls, and shared amenities.
- Long-term fit: Consider future household needs, resale potential, and changing priorities.
Common Buyer Questions
Is it better to live near the beach or inland?
Neither option is automatically better. Inland homes may offer more space and fewer coastal maintenance concerns, while beach-area homes can provide closer access to water and recreation. The right answer depends on budget, insurance tolerance, maintenance preferences, and how often you expect to use the beach lifestyle.
Should buyers visit in more than one season?
Yes. A second visit during a different time of year can reveal changes in traffic, parking, noise, rental activity, weather, and the pace of daily life.
Choose the Community That Fits Real Life
The strongest Pensacola-area purchase balances lifestyle with practical ownership. By comparing community character, total cost, commute patterns, coastal exposure, property condition, and future plans, buyers can choose a home that works just as well on a normal Tuesday as it does on a bright Gulf Coast weekend.
-
 HEALTH2 years ago
Integrating Semaglutide into Your Weight Loss Plan: A Practical Guide
-
 HOME IMPROVEMENT2 years ago
How to Choose the Perfect Neutral Area Rug for Every Room
-
 FASHION2 years ago
7 Celebrity-Inspired Elegant Summer Dresses For 2024
-
 HOME2 years ago
Sandra Orlow: The Teen Model Who Captivated the Internet
-
 LAW2 years ago
Teenage Drivers and Car Accidents in California: Risks and Parental Liability
-
 CONSTRUCTION2 years ago
Construction Site Safety Regulations in New York and Your Rights as a Worker
-
 LAW2 years ago
Post-Divorce Considerations in California: Modifications and Long-Term Planning
-
 FINANCE2 years ago
Digital Asset Management in Florida Estate Planning