HOME
Brook Taube Wells Notice: What You Need to Know

The financial world is abuzz with discussions about the Brook Taube Wells Notice, a topic that has piqued the curiosity of professionals and investors alike. But what exactly does this notice entail, and why should it matter to you? This comprehensive guide is designed to demystify the complexities surrounding the notice, highlighting its significance and what it means for stakeholders involved.
In this post, we will explore the origins of the Wells Notice, its implications for Brook Taube, and the broader impact on investors and the financial sector. Whether you’re a seasoned investor or just entering the financial markets, understanding these elements is crucial for informed decision-making. Buckle up as we break down the details in an easy-to-digest format.
Understanding the Wells Notice
What is a Wells Notice?
A Wells Notice is a formal communication issued by the Securities and Exchange Commission (SEC) indicating that the commission’s staff has made a preliminary determination to recommend enforcement action. This notice provides the recipient an opportunity to argue against such action before it is formally initiated.
The purpose behind a Wells Notice is rooted in fairness and due process. It allows individuals or entities to present their case, potentially influencing the SEC’s final decision on whether to pursue charges. Though not a formal accusation, a Wells Notice often signifies that the SEC has found substantial evidence of potential wrongdoing.
The Significance of a Wells Notice
Receiving a Wells Notice is not an uncommon occurrence in the financial industry; however, it carries significant weight. The notice suggests that the SEC has conducted a thorough investigation and believes there is enough evidence to warrant further scrutiny. This stage is crucial, as it may lead to legal proceedings if not adequately addressed.
For professionals and companies within the financial sector, a Wells Notice can impact reputation, business operations, and investor confidence. Addressing the notice effectively can mitigate these potential repercussions and preserve organizational integrity.
How the Wells Process Works
The Wells process provides a structured opportunity for the recipient to respond. After receiving a Wells Notice, the individual or company can submit a “Wells Submission,” which is a written statement presenting their position and arguments against the proposed enforcement action.
This submission is pivotal as it can influence the SEC’s final decision. While not every Wells Notice leads to enforcement actions, the quality and content of the Wells Submission can significantly impact the outcome. Engaging legal and financial experts is often recommended to craft a compelling response.
Brook Taube’s Connection to the Wells Notice
Who is Brook Taube?
Brook Taube is a well-known figure in the financial industry, recognized for his role as an investment professional and entrepreneur. With extensive experience in managing alternative assets, Taube has made significant contributions to various financial ventures and organizations.
Despite his success, Taube’s name has been recently associated with a Wells Notice, sparking interest and concern within the investment community. Understanding his background provides context to the current situation and its potential implications.
The Circumstances Leading to the Notice
The Wells Notice issued to Brook Taube is reportedly linked to activities within his professional domain. While specific details remain limited due to ongoing investigations and legal considerations, the notice suggests a thorough examination of his business practices and regulatory compliance.
Such scrutiny is part of the SEC’s broader mandate to ensure transparency and adherence to financial regulations. For Taube, addressing the notice involves navigating complex legal and financial landscapes, making strategic decisions crucial.
Potential Consequences for Brook Taube
Receiving a Wells Notice can have numerous implications for Brook Taube, ranging from potential legal challenges to reputational risks. In the financial sector, reputation is paramount, and any perceived regulatory issues can affect investor trust and partnerships.
Proactively addressing the notice and cooperating with investigations can help mitigate risks and demonstrate a commitment to compliance. Taube’s response strategy will likely play a crucial role in shaping the final outcome and his professional trajectory.
Implications for Investors and the Financial Sector
Investor Reactions to the Wells Notice
For investors, news of a Wells Notice can trigger a range of emotions, from concern to curiosity. Investors may worry about the stability of their investments and the potential impact on asset values. It is essential for investors to stay informed and assess the situation objectively.
While a Wells Notice does not always lead to negative outcomes, it highlights the importance of due diligence and continuous monitoring of investment portfolios. Investors should consider the broader context and potential resolutions when evaluating their positions.
Impact on Market Dynamics
The issuance of a Wells Notice, particularly to a prominent figure like Brook Taube, can influence market dynamics. Such developments often lead to increased market scrutiny and volatility as stakeholders assess potential ramifications.
Market participants may adopt a cautious approach, re-evaluating risk exposure and investment strategies. Understanding the nuances of the situation can help investors make informed decisions and adjust their portfolios accordingly.
Broader Regulatory Implications
The Brook Taube Wells Notice also underscores the SEC’s commitment to regulatory enforcement and investor protection. It serves as a reminder of the regulatory framework governing financial markets and the importance of compliance.
For the financial industry at large, this notice may prompt organizations to review their internal controls and compliance protocols, ensuring alignment with regulatory standards. Proactive measures can help prevent similar situations and enhance organizational resilience.
Navigating the Path Forward
Key Takeaways for Stakeholders
For all stakeholders involved, the Brook Taube Wells Notice serves as a critical learning opportunity. It highlights the importance of transparency, compliance, and effective communication in the financial sector.
Stakeholders should prioritize understanding the regulatory landscape and engaging experienced professionals to guide them through complex situations. Collaboration and open dialogue can foster a robust ecosystem, benefiting all parties involved.
Building a Resilient Financial Future
In the face of uncertainty, resilience is key. Organizations and investors alike should focus on building robust frameworks that can withstand regulatory scrutiny and adapt to evolving market conditions.
Investing in compliance infrastructure, fostering a culture of accountability, and staying informed about industry trends are vital steps toward achieving long-term success. By prioritizing these elements, stakeholders can confidently navigate the financial landscape.
Additional Resources and Next Steps
For those seeking to explore more about the Brook Taube Wells Notice and its implications, numerous resources are available for further reading. Engaging with financial advisors, legal experts, and industry analysts can provide valuable insights and guidance.
Staying informed and proactive is crucial for navigating the complexities of the financial sector. By leveraging available resources and adopting a forward-thinking approach, stakeholders can confidently address challenges and seize opportunities.
Conclusion
The Brook Taube Wells Notice is a significant development in the financial world, offering valuable lessons for investors, professionals, and organizations. Understanding the intricacies of the notice, its implications, and potential outcomes is essential for making informed decisions and building a resilient financial future.
By prioritizing compliance, transparency, and continuous learning, stakeholders can confidently navigate uncertainties and contribute to a thriving financial ecosystem. Whether you are an investor, professional, or industry observer, staying informed and engaged is key to success in the dynamic world of finance.
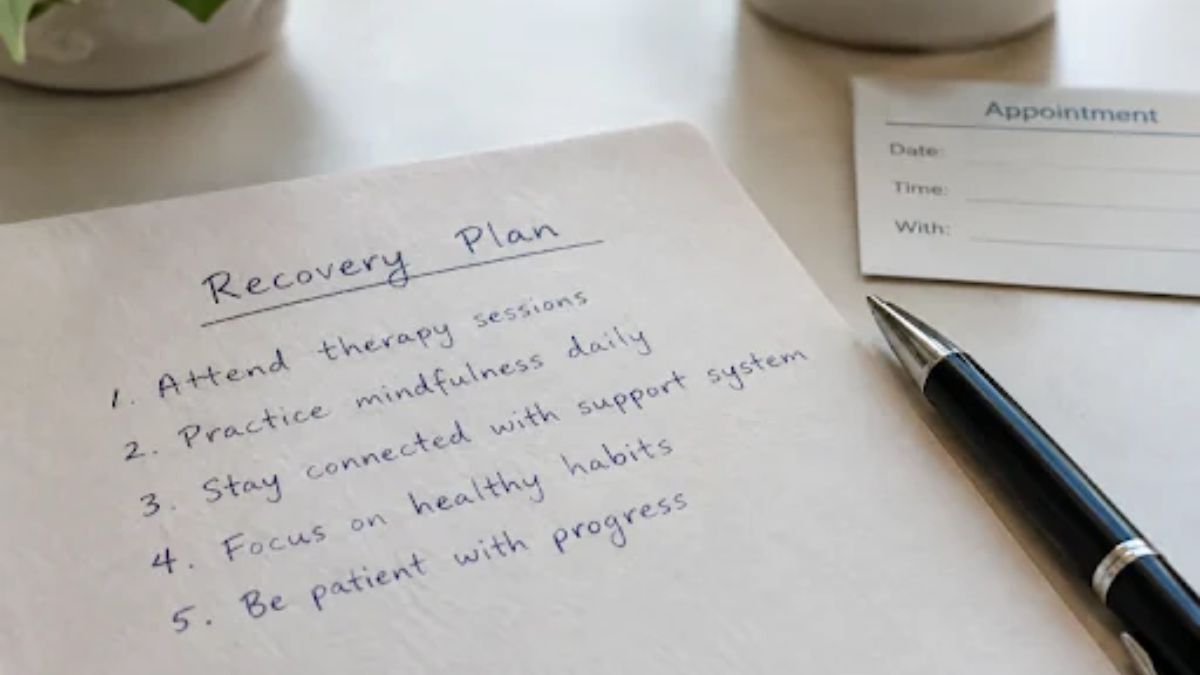
Finishing detox is an important milestone, but it is usually the beginning of the next phase of recovery rather than the end of treatment. For adults who need coordinated follow-up, alcohol addiction treatment services at Desert Mountain Healing IOP combine clinical medication support, counseling, intensive outpatient programming, case management, and recovery planning when appropriate. The Rio Rancho provider serves Albuquerque and surrounding New Mexico communities with an individualized approach that helps connect medical needs with day-to-day recovery goals.
The period after detox can feel both hopeful and uncertain. Physical withdrawal symptoms may improve, yet cravings, stress, relationship problems, mental health concerns, and practical responsibilities can still make recovery difficult. A clear plan creates structure for the days and weeks ahead.
Key Takeaways
- Detox can help a person safely manage withdrawal, but it is generally only the first stage of recovery.
- An effective plan brings together medical follow-up, counseling, routines, and personal support.
- Medication may be appropriate for some people with alcohol or opioid use disorders and should be managed by a qualified clinician.
- Transportation, housing, work schedules, and insurance can affect whether treatment is realistic and accessible.
- Recovery plans should be reviewed regularly and adjusted as circumstances change.
Table Of Contents
- Detox Is Only the First Step
- Build a Care Plan Before Leaving Detox
- Connect Medical and Behavioral Care
- Make Daily Life Work With Treatment
- Plan for Cravings and High-Risk Moments
- Consider Medication Support When Appropriate
- Use Family, Peer, and Community Support
- Review the Plan Over Time
- Common Questions After Detox
Detox Is Only the First Step
Detox focuses on the immediate effects of stopping or reducing substance use, including withdrawal symptoms that may require medical attention. Ongoing treatment addresses a different set of needs: coping with cravings, improving decision-making, treating co-occurring mental health symptoms, repairing relationships, and building a stable routine. As addiction treatment and recovery guidance explains, recovery often involves continuing care and services that support long-term health.
For example, someone may leave detox feeling physically stronger but return to the same stress at home, conflict in a relationship, or social setting connected with past substance use. Planning for those realities can make the transition less overwhelming.
Build a Care Plan Before Leaving Detox
A discharge recommendation is more useful when it becomes a specific, written next step. Before leaving detox, ask what level of care is recommended, when the first appointment will occur, who will manage medications, and what to do if symptoms worsen after regular business hours.
Questions To Answer Before Discharge
- What provider or program will handle follow-up care?
- Has the referral been received and accepted?
- How will transportation to appointments work?
- Are insurance approval, copays, or medication costs likely to create barriers?
- Which records, releases, or prescriptions need to be transferred?
When possible, schedule the first appointment before discharge. Keep the provider’s name, address, phone number, appointment time, and after-hours contact information in one place. With permission, a trusted support person can also keep a copy of the plan.
Connect Medical and Behavioral Care
Recovery can involve both physical and emotional health, so communication among providers matters. Depending on a person’s needs, care may include medical evaluations, medication management, individual counseling, group therapy, intensive outpatient services, case management, mental health screening, family education, and relapse-prevention work.
Coordinated care helps prevent a person from having to manage disconnected recommendations on their own. It also gives the treatment team a clearer view of symptoms, progress, medication concerns, and barriers to participation.
Make Daily Life Work With Treatment
A recovery plan has to fit real life. Work, school, parenting, caregiving, housing, and transportation needs do not disappear after detox. The recovery framework of health, home, purpose, and community can help people consider whether a plan supports the broader conditions needed for stability.
Daily Planning Checklist
- Set consistent times for sleep, meals, prescribed medication, and appointments.
- Arrange transportation before the first treatment session.
- Keep contact numbers and appointment reminders accessible.
- Allow time for work, family responsibilities, rest, and recovery activities.
- Limit avoidable exposure to people, places, or events strongly associated with substance use.
- Build extra time into the schedule for stressful or difficult days.
Plan for Cravings and High-Risk Moments
Cravings and stressful moments are easier to manage when a response plan is already in place. Willpower alone can be difficult to rely on when someone is tired, upset, isolated, or in an environment linked to past use.
Build a Personal Craving Plan
- List common triggers, such as conflict, loneliness, physical pain, payday, or unstructured evenings.
- Identify early warning signs, including skipped appointments, isolation, anger, or racing thoughts.
- Choose one immediate action, such as leaving the situation, contacting a support person, or calling the care team.
- Keep crisis and support numbers easy to find.
- Review the plan with a clinician or trusted person and update it when needed.
Seek urgent medical help for suspected overdose, seizures, severe withdrawal symptoms, serious breathing problems, chest pain, confusion, or immediate thoughts of self-harm.
Consider Medication Support When Appropriate
Medication-assisted treatment is not one medication or a fixed timeline. For some people, prescribed medication may reduce cravings, support stabilization, or help them participate more fully in counseling and recovery services. A qualified prescriber should consider medical history, current symptoms, other medications, treatment goals, and clinical risks.
Medication choice, dose, monitoring, and duration differ from person to person. People should not start, stop, or change prescribed medication without medical guidance. Insurance coverage and local availability may also affect the options a person can access.
Use Family, Peer, and Community Support
Support people can provide practical help without replacing professional care. They may offer transportation, help organize paperwork, provide a calm place to talk, or participate in family education when appropriate. Respect for privacy, boundaries, and treatment goals is essential.
No one person should have to carry the entire recovery plan. A broader network can include clinicians, peer support groups, trusted friends, family members, community programs, and crisis resources.
Review the Plan Over Time
Recovery plans need adjustment. A new job, move, family crisis, medication change, return to substance use, or change in mental health symptoms may call for more support or a different level of care. Missed appointments can also point to practical barriers, such as transportation problems or unstable housing, rather than a lack of commitment.
Monthly Review Questions
- Are appointments and medications accessible?
- Does the current living environment support recovery?
- Are cravings becoming easier or harder to manage?
- Which parts of the plan feel unrealistic?
- What support would make the next month safer?
Common Questions After Detox
Does Finishing Detox Mean Treatment Is Complete?
No. Detox may help stabilize the body, while continuing care can address coping skills, mental health, relationships, routines, and long-term recovery goals.
Can Someone Work While Attending Outpatient Treatment?
Outpatient care may fit around work, school, or family duties. The right schedule depends on clinical needs, stability, transportation, and available support.
What If Substance Use Happens Again?
Contact the treatment team promptly. A return to use may mean the current plan needs additional structure, a new medical assessment, different services, or stronger support.
Conclusion
Detox can open the door to recovery, but the next steps help make recovery safer and more sustainable. A practical plan connects medical care, counseling, routines, support people, and clear responses to difficult moments. The most useful plan is not necessarily the most complicated one. It is the plan a person can understand, access, and adapt as life changes.
Buying a home can feel out of reach when your financial life does not fit the standard pattern of one employer, regular pay stubs, and a long credit history. Families with contract income, multiple jobs, recent moves, or limited U.S. credit can still take meaningful steps toward becoming stronger applicants. Some borrowers may also explore ITIN mortgage loans when traditional documentation or identification requirements do not reflect their circumstances.
The goal is not to make your finances look different from what they are. It is to organize an accurate, consistent picture of how you earn, spend, save, and pay your obligations. Early preparation can help you identify gaps, answer lenders’ questions more quickly, and make a more confident decision about the price range that fits your household.
Why Financial Records Matter
Mortgage lenders generally assess an applicant’s ability to repay a loan by reviewing income, debts, available funds, credit information, and other application details. A credit score is important, but it does not always tell the full story. For example, a renter may have a reliable history of paying rent on time while having few accounts reported to the major credit bureaus.
Organized records help show the pattern behind the numbers. The Consumer Financial Protection Bureau recommends that buyers prepare by reviewing their credit, assessing their finances, setting a home-price budget, and gathering application materials before shopping for a mortgage. This can make it easier to spot issues before they become a time-sensitive problem.
What Nontraditional Financial History Means
Nontraditional financial history is a practical description of circumstances that may not appear neatly in a conventional mortgage file. It can include a thin credit profile, self-employment, contract work, income from several jobs, a short U.S. credit history, or recurring payments that are not consistently reported on a credit report.
- Self-employment, freelance work, tips, commissions, or seasonal earnings
- Income received through more than one employer or client
- Verified rent, utility, insurance, or phone payments
- Recent relocation or newly established credit accounts
- Documented savings built gradually over time
Documents to Gather Before Applying
Create one secure digital folder and keep paper copies when useful. A lender may request different items depending on the loan and borrower, but a well-organized file can reduce back-and-forth questions.
- Recent bank statements and earnings statements
- Pay stubs, tax returns, tax transcripts, 1099 forms, or business records when applicable
- Invoices, contracts, and payment records for contract or self-employed income
- Rental receipts or a landlord-provided payment history
- Utility, insurance, and other recurring payment records
- Statements for current debts and monthly obligations
- Identification documents and proof of the source of down payment funds
How Alternative Credit May Help
Some lending programs and lenders may review verified payment records beyond standard credit accounts. These records can help demonstrate a pattern of meeting recurring obligations, especially when a borrower has limited traditional credit. They are not a substitute for the full application review, and acceptance varies by lender and loan program.
Records That May Be Useful
- Rent payments made through a traceable method
- Electric, gas, water, internet, or phone bills
- Auto, renters, health, or other insurance payments
- Child care, tuition, or similar recurring obligations
Keep records that clearly identify the account holder, the payment amount, the due date, and the payment date. Cash payments can be difficult to verify without receipts, bank withdrawals, or a written payment history from the recipient.
How to Organize Different Income Sources
Families with multiple income sources should make the connection between the work performed and the money received easy to follow. A contractor, for example, can keep invoices, signed agreements, deposit records, and tax documents together to show how business income is deposited into a personal account.
- List every household income source and how often it is paid.
- Separate business and personal transactions when possible.
- Keep invoices, contracts, and deposit records in date order.
- Be ready to explain large or unusual deposits.
- Avoid moving money between accounts without retaining a clear paper trail.
How to Build a Realistic Homebuying Budget
The amount a lender may approve is not always the amount that feels comfortable for your family. Build your budget around the full monthly housing cost, including principal and interest, property taxes, homeowners’ insurance, mortgage insurance if required, homeowners’ association dues if applicable, utilities, and expected maintenance.
Also plan for upfront costs such as the down payment, closing costs, moving expenses, and immediate repairs or purchases. Review several months of actual spending before setting a target payment. The CFPB advises buyers to compare mortgage offers from multiple lenders, which can help households evaluate loan terms and costs rather than focusing on one advertised rate. This gives buyers a practical framework for that process.
Questions to Ask a Mortgage Professional
- Which documents can be used to verify my income?
- Can verified rent or utility payments be considered in this program?
- How much payment history is needed?
- How are self-employed, contract, commission, or seasonal earnings reviewed?
- Which funds may be used for the down payment and closing costs?
- What fees are due before closing, and what costs are included in the estimate?
- Would a co-borrower change the available options?
Mistakes That Can Slow Down an Application
- Applying before checking credit reports for errors or missing information
- Leaving large deposits unexplained
- Taking on new debt or opening unnecessary credit accounts before closing
- Changing jobs or income structure without discussing it with the lender
- Using cash without maintaining receipts or other documentation
- Underestimating taxes, insurance, repairs, and moving costs
A Step-by-Step Preparation Plan
- Set a price range. Base it on the full monthly cost and your household budget.
- Review credit and debts. Correct errors and understand existing monthly obligations.
- Build a document folder. Save bank, income, tax, rent, and payment records in one place.
- Track savings. Keep a clear record of where the down payment and closing funds come from.
- Speak with qualified lenders. Ask how each one reviews your specific financial records.
- Keep records current. Continue documenting income, payments, and account activity through closing.
Final Thoughts
Homeownership preparation is not limited to households with a long, conventional credit history. Clear records, steady financial habits, realistic budgeting, and early conversations with mortgage professionals can help families present a more complete application. Start by organizing the facts, protecting your savings, and choosing a home payment that supports your life after closing.
HOME
How to Plan Laser Hair Removal Around Skin Tone, Hair Growth, and Seasonal Sun Exposure in Centennial, Colorado

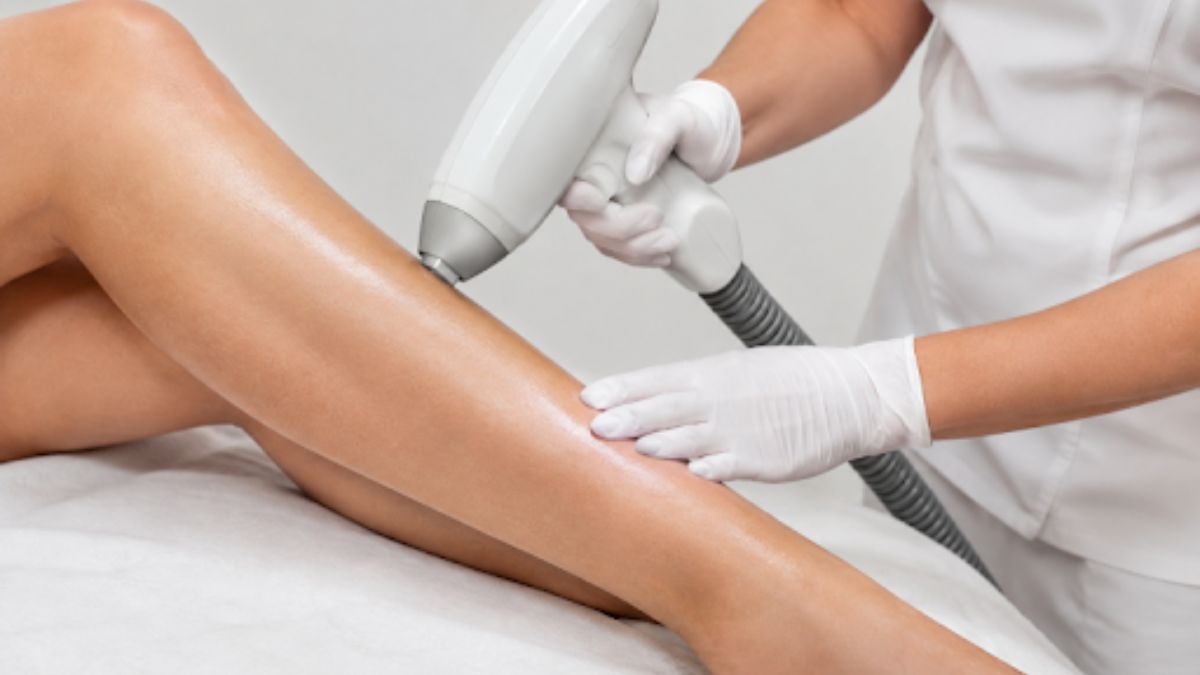
Planning laser hair removal in Centennial, Colorado, involves more than choosing a convenient appointment date. The timing should account for your hair growth pattern, your skin’s current condition, and how much sun exposure is likely during work, recreation, travel, and daily life along the Front Range.
For local clients comparing options, Hair To Bare South offers laser hair removal services Centennial, CO with treatment options organized by small, medium, large, and extra-large areas. Its service information helps Centennial-area clients understand the range of areas that may be treated and why a consistent, safety-focused plan matters when working toward long-term hair reduction.
Why Treatment Timing Matters
Laser hair removal is not typically a one-visit solution. The laser is designed to target pigment associated with the hair and follicle, but only some follicles are in the most responsive stage at a given time. That is why appointments are commonly spread across a series rather than scheduled back-to-back.
According to the American Academy of Dermatology’s laser hair removal guidance, many patients can be treated about every four to six weeks, although the appropriate interval depends on the person and area treated. A provider should set the schedule based on visible regrowth, skin response, and treatment goals.
How the Hair Growth Cycle Affects Results
Hair moves through several broad growth phases. Understanding them can make the treatment process feel less mysterious.
Active growth
During the active growth stage, often called anagen, the follicle has a stronger connection to the hair being treated. This is generally the stage in which laser treatment is most useful.
Transition and resting
In the transition stage, growth slows. In the resting stage, the follicle does not produce a new visible hair in the same way. Since neighboring follicles can be in different phases, one session cannot address every hair at once.
Consistency is more valuable than rushing. Scheduling too frequently does not necessarily create faster results, while long, irregular gaps can make it harder to follow a clear plan for recurring growth.
Skin Tone, Hair Color, and Hair Texture
Darker, coarser hair often provides a clearer target because it contains more pigment. Fine blonde, gray, white, and some red hair can be more difficult for laser-based treatment to detect and reduce. That does not mean a consultation is pointless, but it does mean expectations should be discussed honestly before treatment begins.
People with darker skin tones may be candidates for laser hair removal, but device selection, settings, and provider experience become especially important. Ask how the provider evaluates skin coloring and how they reduce the risk of burns, irritation, or unwanted pigment changes. A careful consultation should never treat skin tone or hair type as an afterthought.
Seasonal Planning for Centennial Sun Exposure
There is no single best season for every person, but Centennial’s bright weather and outdoor lifestyle can affect the practical side of planning. Ski days, patio time, hikes, golf, and warm-weather trips can all increase sun exposure, including when temperatures feel cool.
- Winter: Less exposed skin and fewer tanning opportunities may make aftercare easier for some people.
- Spring: Starting early can provide time for a series of sessions before summer activities become frequent.
- Summer: Treatment may still be possible, but it requires careful communication about recent sun, tanning, and travel plans.
- Fall: This can be a practical point to begin or resume a treatment series after a more sun-intensive season.
The importance of planning ahead for warmer weather is especially relevant when you expect pool days, vacations, or prolonged outdoor events. Recent tanning, including indoor tanning and self-tanning products, should be disclosed so the provider can determine whether treatment should proceed or be postponed.
Why Treatment Area Changes the Timeline
Small areas such as the upper lip, chin, or underarms can take less appointment time than the legs, back, or chest. However, a shorter appointment does not always mean a shorter overall course of treatment. Hair density, thickness, and hormonal influence can vary substantially from one body area to another.
For example, someone may notice meaningful changes in underarm hair before seeing the same degree of reduction on the legs. Facial hair can require added patience because it may be finer or influenced by hormonal changes. Maintenance visits may be useful for some people after the initial series, particularly when new growth develops over time.
Simple Steps to Prepare
- Avoid tanning and follow the provider’s instructions about sun exposure.
- Share medications, skin conditions, recent cosmetic procedures, and any history of unusual scarring.
- Ask whether shaving is recommended before your appointment.
- Avoid waxing, plucking, or epilating when the provider advises leaving the follicle intact.
- Arrive with clean skin and avoid products that may irritate the treatment area.
- Wear soft, comfortable clothing that will not rub against freshly treated skin.
Questions to Ask Before Booking
- What experience do you have with my skin tone and hair type?
- Which laser or light-based device will you use?
- How many appointments may be appropriate for this area?
- How far apart should my sessions be scheduled?
- What should I avoid before and after each appointment?
- Which side effects are expected, and which require follow-up?
- Would a consultation or test spot be appropriate?
Realistic Results and Long-Term Planning
It is more accurate to think in terms of permanent hair reduction than guaranteed removal of every hair forever. Results differ by skin tone, hair characteristics, hormonal changes, area treated, device, and appointment consistency. A trustworthy provider explains those variables clearly instead of promising identical results for everyone.
A strong consultation includes a review of recent sun exposure, a plain-language timeline, discussion of possible side effects, and a plan tailored to the individual. In Centennial, the best laser hair removal schedule is usually the one that protects your skin, fits your calendar, and gives each treatment enough time to work.
-
 HEALTH2 years ago
Integrating Semaglutide into Your Weight Loss Plan: A Practical Guide
-
 HOME IMPROVEMENT2 years ago
How to Choose the Perfect Neutral Area Rug for Every Room
-
 FASHION2 years ago
7 Celebrity-Inspired Elegant Summer Dresses For 2024
-
 HOME2 years ago
Sandra Orlow: The Teen Model Who Captivated the Internet
-
 LAW2 years ago
Teenage Drivers and Car Accidents in California: Risks and Parental Liability
-
 CONSTRUCTION2 years ago
Construction Site Safety Regulations in New York and Your Rights as a Worker
-
 LAW2 years ago
Post-Divorce Considerations in California: Modifications and Long-Term Planning
-
 FINANCE2 years ago
Digital Asset Management in Florida Estate Planning